Showing posts with label policy. Show all posts

19 Mar 2012

Open Letters in Response to the Budget

  
As mentioned in my post on the Union Budget FY 2013, I would like to share these 2 Open Letters, addressed to Mr. Finance Minister, in response to the Budget. The reason I picked these two is that they offer very different vantage points; one is from the perspective of a student, and the other is from the perspective of a tech-entrepreneur. Both letters provide good insight on the kind of impact the Budget's proposals would have on everyone, and how this Budget, just like all its predecessors, is not a proactive one.


1. Why I didn’t like the budget: A student’s view of Budget 2012 

Dear Finance Minister,

I hated hearing that long budget speech of yours. Who wants to know if there was an increase in the paddy yield? All I cared about was going to the US, getting a foreign degree and making some money. But do you care?

You are now giving my parents second thoughts about sending me abroad. So what if there’s no service tax on pre-school and high school education? That’s in India. Of course I am not bothered!

You increased the service taxes on all other things from 10 percent to 12 percent. This obviously means my father has to pay more for my GRE tuition and TOEFL tuitions.

For all you know, he might just decide to keep his money in his savings account for it to grow; as you announced that will give him higher income tax exemptions on it and maybe he’ll send me to a college in India. That’s not what I want.

He’s already talking about reducing my pocket money and now you have given him good reason to do that.

The education loan I would take to study abroad won’t come cheap. On top of that, eight years is all I have to repay back the loan. Eight, just eight? Couldn’t you, our finance minister, increase it to 10 years, at least?

Yes, I know you are allocating funds to research centres in India, but I still want to go abroad to study.

You promised to ensure better flow of credit to us, by proposing a Credit Guarantee Fund. But when will that be set up? I want to go abroad the next year as soon as my I am done with high school, but this ‘credit thing’, I am sure, will not be set up so soon. The way India functions it will take another five years. Can you promise you will set it up this year?

You also proposed to set up more schools in rural areas. Ok, I understand development. But what about women’s development? Girl child education and all that? Nothing.

No easy loans even for the girls, while the interest rates will continue to remain at par with the boys.

And even if I forget education abroad for a moment, what about that bike that my father was supposed to give me next month? You’ve made that expensive too. And now that will have to wait too.

Sincerely patient,

A student who did not like your budget


2. Mr. FM, why don't you ever think of entrepreneurs?

Dear FM,

I looked you up on Facebook but found a cold 'page'. I checked on Twitter, but came across some fake ids. I searched on Linkedin but you don't seem to be there. I gathered that I can't hang out with you on these internet-mobile places I hang out in, because you probably don't visit them!

Let me come to the point. I read your budget speech with interest (all 14,234 words of it). Amidst your Pacific Ocean of words, I found:

The word 'Startup' mentioned 0 times.
The word 'Internet' mentioned 0 times.
The word 'Mobile' mentioned 2 times.
The word 'Entrepreneur' mentioned 3 times.

Now, the word 'Farm' is mentioned 16 times and the word 'Agriculture' is mentioned 18 times. Sir, let me share with you some interesting trivia. In another country, a couple of years ago, an entrepreneur created a new agricultural community that invited farmers from all over the world.

The address of the farm was the Internet. The place was 'Farmville'. Believe it or not, this Farmville 'thingy' generated `300 crore of revenue in the first year. About 5 crore farmer 'players' signed up! When the Haiti earthquake struck, this community actually garnered money and sent it to Haiti. To cap it all, the company, Zynga (that started this virtual agricultural business), is actually listed on the stock exchanges and is currently worth Rs 5,000+ crore!

Sir, just pause and think if Zynga was created in India. You, sir, would have earned juicy service taxes, revenues from corporate taxes, even would have a nice new age listed company on our otherwise boring bourse. The point I am making, is that new age businesses of the internet and new age entrepreneurs like myself, deserve a bit more attention from you. Because we attract venture capital, we employ people, we generate revenue, we pay our taxes and sometimes, even sell our companies and bring the money home!

Sir, I don't like wearing suits and ties; or coming to meet you in Delhi. But I can request you to help us in a few critical issues, on behalf of the Internet, entrepreneurial community.

Consider These Two Examples:
A month ago, a team of four young entrepreneurs came to meet me. In a couple of minutes, I figured two things about them:

i) They came from families that a decade ago, would have never dreamt that their children would be graduates, speak fluent English and earn more money than their fathers ever did, all at a young age.

ii) This quartet was smart. I mean really smart. Smarter than anyone I had ever met!

This was a goosebumpy moment for me. It signalled that the 'Indian Dream' was working. Despite all our odds, we were producing local 'chaap' Einsteins! These four friends told me that they were quitting their jobs and becoming Internet entrepreneurs. And they presented an idea to me that blew my mind. They wanted me to mentor them, and I readily accepted. I felt it was a 'Googlesque' moment (what may have transpired when Google started up).

A week later, I got an SOS from one of them. They wanted to acquire a web domain (a site name) that was available on a foreign auction site since it was critical to their business. They requested I help them. I readily agreed. What transpired is something I want to bring to your attention.

To buy the domain, I needed to transfer about $1,000 to a German company. They accept only 'PayPal' payments, but PayPal is not available in India. When I wrote to the Germans they were flabbergasted! They said, "PayPal 'is' the global payment platform for small transactions".

But I had to tell them the Indian government had severe restrictions in letting them operate here. I begged them to allow me to wire the money to them. They agreed. When I started the transfer, I realised that it was 'impossible' for a startup to manage the process using the Indian banking processes! I had to sign some 8 forms, get my CFO and his team to 'solve some major paperwork crosswords' and also pay for certification charges.

Finally, I did get the domain, but trust me, on their own, this hot start up would never have made it. The over-regulated and complicated banking laws of India would have killed this 'google' in-the-making even before they started up.

After many years, I was able to woo a senior gaming expert in the US to join me. All he wanted was independence and esops. I gave him independence on day one, but the procedures to carve out esops for a foreign national to be employed by an Indian company became a mystery that would make even Dan Brown's Da Vinci Code look like an amateur essay! It took a good four months to solve the riddle, and I went through hell to keep Mr Gaming Rockstar motivated. He liked me and hung on, but now he is really nervous about India and its laws.

Sir, the number of do's, don'ts, regulations, forms, certifications, validations, permissions, etc that small, startup internet companies require to comply with, kill our energy, excitement and enthusiasm to grow. We need special treatment.

Let me say, that we are like delicate flowers. We need special farming rules to grow. Give us those, and I promise you, when we bloom, your treasury will be full. Not just with revenues but also the scent of a new and fresh Indian Industry!

(The writer is a digital entrepreneur)


18 Mar 2012

India's Union Budget FY 2013


The run-up to the Union Budget has seen a plethora of ‘experts’ (bankers, corporate executives, investors, economists, journalists, etc.) voicing their opinion of what the Union Budget FY2013 should look like. The Union Budget is probably the most hyped up event in the economic calendar. From being a simple event of the government declaring the profit and loss account of the public finances, it has undergone a metamorphosis, whereby the government now provides a snapshot of the nitty-gritties of the economy, policy ingredients, and guidance for the next fiscal year. Nobody gains from this parliamentary Budget session as much as the media. In fact, judging by the past few years, the Budget has been more of the TRP (Television Rating Point) event than a GDP (Gross Domestic Product) event.

 
Budget Day in India is somewhat of a close follower of the British counterpart. For many years in Britain, the Chancellor of the Exchequer ceremonially enters the House of Commons with a Victorian-era ‘budget box’ briefcase. In similar fashion, Indian Finance Minister Pranab Mukherjee clutched his red leather briefcase as he entered the Indian Parliament building. Mr. Mukherjee presented India’s 81st annual Budget on March 16th; Individually, it was his seventh, the second highest by any Finance Minister in India. Several ‘experts’ were hoping the budget would introduce the much-awaited reforms that would spur economic growth, and bring back the investor confidence. The key reforms anticipated by the markets included:
  1. A revamp of Tax-structure by introducing Goods and Service Tax (GST) and a Direct Tax Code (DTC)
  2. Allowing Foreign Direct Investment (FDI) in sectors such as Aviation, Retail, and Insurance
  3. Trimming the fiscal deficit
  4. Removing infrastructure bottlenecks
  5. Breakup of the state-run Coal monopoly
  6. Cutting back on subsidies (Fuel, Fertilizer, and Food)
  7. Maybe even some tax relief for the middle class

However, one doesn’t need to be a genius to realize that making everybody happy was impossible. The FY-2013 Budget, like most of its predecessors, stuck to the age-old trend of taxing consumption, raising taxes for existing taxpayers to pay for the handouts given to the impoverished, bail-out ailing sectors, and optimistically talk about reforms to come. The emphasis was on Inclusive Growth, with increased spending on agriculture, healthcare, and education. Little wonder that his choice of literary quote was from Hamlet: “I must be cruel, only to be kind”, compared to Dr. Manmohan Singh citing Victor Hugo in 1991, “a reformed and confident India was an idea whose time had come”.

The FM started his budget speech reminding everyone of the tough global economic environment (high oil prices due to tensions in the Middle East, European Crisis, the usual suspects really). Then he moved on to present India’s economic performance. FY2012 GDP growth rate pegged at 6.9%, compared to 8.4% in the previous year. GDP growth for FY2013 expected to be around 7.6%. Then he moved on to talk about fiscal consolidation, saying that issues regarding public finance – something that investors and the RBI have been demanding for quite some time now – would be addressed. The fiscal deficit, targeted at 4.6% of the GDP, was likely to be around 5.9% for the year ending March 2012. However, factoring in the states’ deficit, and off-balance sheet items, the overall deficit could touch 9%. He announced the target for next fiscal year to be 5.1% (and below 4% in 3 years), which would be achieved on the back of increased service and excise taxes, and subsidy expenditure reduced to 2% of the GDP (and 1.7% in 3 years) from about 2.7% now. It also set a divestment target of Rs 300 billion for FY2013 compared to its FY2012 target of Rs 400 billion, of which it only managed to raise Rs. 139.1 billion (through an FPO of Power Finance Corp. and a 5% stake auction on Oil &Natural Gas Corp.)

He also tried to excite the financial markets by proposing Qualified Foreign Investors (QFIs) access to Indian Corporate Bond Markets; and incentivize greater participation by retail investors in equity markets through Rajiv Gandhi Equity Savings Scheme, which would give them 50% income-tax deduction upto Rs. 50,000. Then he announced that small investors could e-vote in companies. Obviously their e-vote would not be sufficient to stop the Government from looting PSUs (Remember ONGC?). Furthermore, he lowered the Securities Transaction Tax (STT) to just 0.1%.

Mr. Mukherjee then moved on to talk about the bottlenecks in the economy:
  • Provided Rs 158.88 billion for recapitalization of public sector banks, regional-rural banks, and other financial institutions like National Bank for Agriculture and Rural Development (NABARD)
  • Allowed another Rs. 600 billion worth of tax-free bond issuances to fund infrastructure projects
  • Cut customs duty on imported coal to ensure fuel supply for power generation
  • Directed Coal India to sign long-term Fuel Supply Agreements (FSAs) with Power plants
  • Allowed Airlines to raise more foreign loans (ECBs) for Working Capital
  • Allowed ECBs for Capex Requirements of Infrastructure Projects (more specifically, power projects, roads and highway projects)
  • Set up a Credit Guarantee Trust Fund and allowed ECBs for Low-Cost Housing Projects to address shortage of affordable housing in many cities
  • Provided for Telecom Towers to get viability gap-funding
  • Increased funding for National Rural Health Mission (NRHM) to Rs. 20.8 billion
  • Announced a “White Paper” is being prepared to deal with on black money (illicit funds) stashed both, at home and abroad
  • Increased Defense spending by 17% to Rs. 1.93 trillion
  • Provided Rs. 255.55 billion to the Right to Education, a 21.7% yoy increase, and also proposed setting up a Credit Guarantee Fund for students

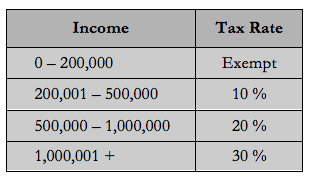
Finally he spoke about Taxes. On personal taxes, he enhanced the basic limit for tax exemption to Rs. 200,000, and expanded the 20% tax slab upto Rs. 1 million. The new tax slabs is illustrated below. Furthermore, there would be no separate tax slabs for women. Interest-income upto Rs. 10,000 from savings account in banks or post offices would now be tax-free. But custom duty on Gold and Platinum were increased (understandably so, to curb gold imports and to channel that money into more productive areas of the economy). Additionally, Sin tax increased on some tobacco products.


 There was no change in corporate tax rates. Broadly, service taxes and general excise duties were hiked to 12%. However, peak excise duty remains unchanged at 10%. This surely would be inflationary as services account for 59% of our GDP. I have compiled a chart to illustrate which goods or services will now cost more and which will cost less.


Overall, Union Budget 2013 was expected to deliver big-bang reforms. But all it had to offer was the traditional mix of more public spending and reshuffled taxes, none of which will be revitalize the stalled engines of economic growth. However, one announcement that was big bang in nature was that of General Anti Avoidance Rules (GAAR), a proposal to amend tax laws to retroactively levy capital gains tax on Indian assets (even on deals that take place abroad by foreign entities). This would apply to transactions as far back as April 1962. It appears that the amendment is principally aimed at taxing Vodafone, but this could well scare off foreign investors – the same people who fund India’s current account deficit; the same people that the Indian Government has been trying to woo.

Brief Background on Vodafone Case:

The British telecom giant bought an Indian operator from Hutchison Telecom of from Hong Kong in an offshore deal in 2007 for $11 billion. However, the Supreme Court of India, in January 2012, ruled that Vodafone should not have to pay a $2.2 billion tax that the Indian government claimed.

Later in the day, Mr. Mukherjee tried to explain that the government was only clarifying the 1962 tax law, and trying to close a loophole that allowed some companies to structure transactions in tax-havens such as Mauritius, purely to avoid paying any capital gains tax. “We are making it very clear that it is the law of the land — this is the intention of the legislature,” he said on NDTV, a news channel.


My Reaction
  
The Union Budget continued with the present Government’s theme of Inclusive Growth. Thankfully however, it refrained from announcing any extremely populist measures, especially considering its poor performance in recent state elections. Instead, it focused on fiscal consolidation. However, no big-ticket reforms were announced either. It seems like whatever additional revenues they’re raising will all be diverted to welfare programs and wasteful subsidies. So in short, our government continues to play Robin Hood.

The government has missed targets before. Furthermore, the last 2 quarters have seen so many revisions that government estimates can no longer be considered a reliable source. There is something really wrong with the way the official statistics are calculated and maintained. Hence pardon my cynicism but I’d take these Budget numbers with a pinch of salt too.

One major takeaway is that the government has missed an opportunity to deliver reforms and jumpstart the productive engines of the economy. I was not expecting the budget to deliver too much, but at least a few reforms were desperately needed. Politics is once again driving the nation at the detriment of economics.

We witnessed this two days ago as well, when a coalition ally Ms. Mamata Bannerjee, populist leader of West Bengal based Trinamool Congress, demanded the Railway Minister (who belongs to her own party) to be fired. 


His crime? Proposing a fractional rise in rail fares to modernize Indian Railways and improve its safety and hygiene. The rail budget was forward-looking, and the fare-hike was very modest, ranging from 2p – 30p per kilometer (or 0.04 – 0.6 cents per km); the fares had not been revised since 8 years. But by proposing this, Rail Minister Mr. Dinesh Trivedi had apparently “gone against the Trinamool Congress Party’s DNA” and that was unacceptable. Imagine their reaction if the government proposed privatizing the railways.

With such obstructing allies, it would be near impossible for the Congress to carry out any significant reforms even if they had a stomach for them. Another problem is that India Inc is a spoilt bunch that loves to sulk; hence business and investment climate will not improve until some policy action from the government. This budget failed to do that. The measures announced were marginal at best. It didn’t help RBI either. The central bank is terrified that inflation would pick up again, reflecting a host of supply-side constraints ranging from agricultural supply chain to inadequate infrastructure.

So what should the Budget have focused on? Even taking baby-steps, but in the right direction, can go a long way to fixing things. In addition to all that Mr. Finance Minister announced, he should have formed a Priority Group to maneuver the following:


  1. Raise diesel prices, incrementally and quietly, but offset that by matching cuts in the tax on diesel. That way, the fiscal hole starts getting plugged, and the consumers don’t feel much of a pinch.
  2. Set-up a facility to fast-track land acquisition and environmental clearances. This would kick-start the implementation of stalled projects, which would create employment along with boosting infrastructure, and housing markets, financial markets, and business sentiment – and all this without investing a single new penny.
  3. Present a draft on GST and DTC, outlining how the overall economy (include every stakeholder) would benefit from it. Start discussions with an established deadline for the rollout.
  4. As of now, India has only 790 diplomats and ambassadors, compared to about 3,000 in Brazil, over 6,000 in China, and well over 20,000 in America. While this may not have much of a direct impact on Indian’s finances (except their payrolls), it does increase India’s presence in different nations. This not only helps in economic ties, but also strategic ties. For a nation trying to strengthen its global footprint, India is severely under-represented on a diplomatic level.

In a separate post, I would like to share 2 open letters addressed to Finance Minister Pranab Mukherjee in response to his budget announcement. They sum up pretty well how some segments of the economy will be affected. A transcript of his BS (I mean Budget Speech) can be found here:

12 Feb 2012

The Hullabaloo over 2G Licenses

Last year, Time Magazine listed the Indian Telecom Scam 2nd (after the Watergate Scandal) in the “Top 10 Abuses of Power” list. Considering that it has been making headlines since 2010, I suppose most of you know the details of the scandal. However, for those just tuning in, I thought I’d do a post featuring the 2G Licenses and Spectrum Scandal.

What happened?

In 2008, A. Raja, the erstwhile Minister for Communication and IT, decided to allocate 2G licenses and spectrum to several telecom companies, some of whom did not meet the basic requirements to be granted a license. Furthermore, he sold the licenses and spectrum at apparently throwaway prices, causing the exchequer to suffer from revenue losses, estimated up to Rs. 1.76 Trillion ($ 35.2 Billion) according to the Comptroller and Auditor General of India. Interestingly, Kapil Sibal, the incumbent minister of Communication and IT, dismissed the estimates calling them meaningless “notional” figures. Either way, this led to several new players entering the market, and the increased competition (read: price wars) meant lower tariffs for users, and squeezed the profitability of the incumbent players. 


The matter was mute for a couple years of until 2010, when during the 3G license and spectrum auctions, the government realized the amount it had lost in 2008. This incident of poor governance was termed as another scam by our particularly hardworking media. After much political ruckus, the Supreme Court of India declared the allotment as “unconstitutional and arbitrary” and cancelled all the 122 licenses issued by A. Raja. According to the Apex court’s judgment, A. Raja “wanted to favor some companies at the cost of the public exchequer" and "virtually gifted away important national asset" It is worth noting that the Telecom Policy does not have any specific provision for the licenses or spectrum to be auctioned off, and it was only in 2010 that an auction process was deemed to be the most appropriate method of allocating national resources.

Cancelled Licenses and Affected Parties

 
These firms, especially the foreign players, have complained that the Supreme Court ruling disregards the interests of the business community. Furthermore, it is unfair as it makes businesses suffer for what is in essence the Government’s gaffe.  They also said that such moves would make foreign investors hesitant and cautious against investing in India, and this would hurt the nation in the long term.

So what are the implications?

The cancellation of the 122 licenses will affect close to 45 million people around the country (roughly 5% of the total active user base) who will see their services go off. However, the court has given the companies 4 months, so the users will have some time to switch to a different service provider. As for the companies, they are left with 3 options. First, they can go to court and appeal against the verdict (a very lengthy and expensive undertaking). Alternatively, they could bid for the licenses and spectrum (whenever the auctions happen). Or finally, they could exit the Indian telecom market altogether. As for the incumbent players such as Vodafone and AirTel, it is an opportunity to increase their subscriber base, and also a chance to bid for more spectrum. The sector overall will hence see some much needed consolidation, and with competitive pressure reduced now, the unsustainable price-wars can end and the profitability of the firms would increase too.

Personal Take

At just point, I would like to highlight a couple of points, and let you assess the event at your own terms.

Firstly, If 2G spectrum was to be auctioned (like 3G was, and 4G seemingly will be), the government would get more revenues (only to give out more subsidies in my opinion). But would the tariffs be as low as they are? Would your milkman, driver, domestic helper, fruit vendor, etc. all be able to afford it? Would your life be more convenient or less if that was the case?

Secondly, since the spectrum was allocated on a “First Come First Serve” basis instead of an auction, many new players were granted license and spectrum. As a result, incumbent players such as Vodafone and Airtel who have a larger subscriber base were left with too little spectrum to work with while the newer players who were unable to build a sizable subscriber base were sitting idle on precious resource. So this not only prevents the players from achieving economies of scale, but it also translates to poor quality of network coverage for the 800 million mobile phone users across the country.

Thirdly, the scam has further tainted the image of the Government. However, one should really take a step back, and think if this was really as scandalous a misdemeanor as it seems? After all, it did make mobile usage more affordable to the masses. Would 3G (which was auctioned to service providers for Rs. 670 billion or $ 13.4 Billion) be able to achieve the same reach in India’s price elastic telecom market?

Finally, considering as telecommunication and connectivity as a vital infrastructure of the nation, it was an industry that grew at an exponential pace for some time, but that growth has now halted. Little room to expand due to over-competition has led to unsustainable business models. Hence, some consolidation could do wonders for both, consumers as well as the businesses.

The 2G licenses of 2008 were issued at 2001 prices, on a first come first serve basis rather than an auction.  

So, at this point, would you call it a scam or a blunder ?

Corruption or mere Inefficiency ?


I will let you decide for yourself . . .

27 Jan 2012

India Macroeconomic Snapshot 2011

 
For almost 2 years, India’s Central Bank has been busy battling Inflation, even at the cost of Economic Growth. However, instead of being commended on their efforts to tame this stubbornly sticky inflation (which is clearly a product of Supply Constraints and Fiscal Mismanagement), the RBI has been heavily criticized for the slowdown in GDP growth.
In response to the slowdown, the RBI cut the Cash Reserve Ratio – the percentage of deposits that banks must keep with the central bank – by 50 bps (0.5%) in its review on Jan 24, a move that would release Rs. 32,000 Cr ($ 6.5 billion) into financial system. In his policy statement, RBI governor D. Subharao said, “the growth-inflation balance of the monetary policy stance has now shifted to growth, while at the same time ensuring that inflationary pressures remain contained”.
Slowing GDP Growth
According to the official estimates, the GDP grew at a mere 6.9%, compared to 8.4% in the previous year. The slowdown was mainly driven by the manufacturing sector, where growth slowed down from 7.8% last fiscal to a meager 2.7%. Other sectors have fared poorly as well with the Industrial output slipping into negative territory at -5.1% in October before bouncing back to 6.8% in November, mostly on account of a large base-effect. Strapped for funds, core infrastructure sector too saw dismal growth at 0.3%, owing to poor execution of projects.
Inflationary Pressures
Averaging around 9%, throughout the year 2011, headline inflation has been well above the comfort levels of the Government and RBI. While their desired range for headline inflation is 5 – 5.5 %, that range has continuously been breached every year since 2005 – 2006. However, much to everybody’s relief, Food inflation declined to lowest in 6 years (6 years – what a coincidence) albeit thanks to a strong base-effect, and seasonal impact. Since monetary actions take about 4-6 months to show results in the economy, there is some respite for 2012 for inflation to be contained. However, considering the risk of oil prices spiking up, the Central Bank will have to be extremely careful and ensure that inflationary headwinds have genuinely subsided before adopting any stimulus measures throughout 2012.
Burgeoning Fiscal and Current Account Deficits
Another alarming issue for the economy has been its mounting fiscal deficit. The previous Union Budget (FY 2011-2012) had set a target of the fiscal deficit at 4.6% of GDP. However, the fiscal deficit during the first half the fiscal alone was 85.6% of the full-year target. Hence, it is quite clear that the government is set to miss the target, and the deficit is more likely to be around the 5.2% mark, or perhaps more if oil prices rise and/or tax revenues decline (I believe that both events are highly likely, and a deficit of around 5.6% or more should not come as a surprise). With tax collections sluggish, and divestment ambitions foiled by poor market conditions, the government has no option but to borrow more to pay for its ever-growing subsidies bill. In doing so, it essentially mopped up most of the funds in the market, and crowded out private sector investments (i.e. increased interest rates by excess borrowing in the money markets). Rising oil and fertilizer prices and the implementation of the Food Security Bill are all going to further increase the subsidy burden for the government. With a tax base of less than 10% of the GDP, the picture doesn’t look very bright.
To make matters worse, high interest rates, big-ticket scandals, and the government’s reform-inertia had dampened the business environment to such an extent that manufacturing and industrial production plummeted. Exports growth was very trivial (due to economic slowdown in major export destinations), and was merely a fraction of the sharp growth in imports (thanks to robust domestic consumption demand), thereby worsening the trade balance. In addition to the worsening trade-balance, imports of Oil and a huge appetite for Gold (India imported 969 Tons in 2011) dented the Current Account Deficit even further. In fact, Oil and Gold together account for about 70% of the nation’s Current Account Deficit. Furthermore, high interest rates dampened corporate investments, and foreign capital inflows dried up too. All this put pressure on the nation’s foreign exchange reserves, which reflected on the Indian Rupee.
Currency Woes
2011 was a challenging year for the Indian Rupee, which depreciated 16% in 2011 (its biggest annual fall since 2008) and was the worst performing Asian currency of the year. Concerns about the rising fiscal and current account deficits amidst an uncertain global environment, loss of confidence in the Indian reform process, doubts over its growth momentum and stubbornly high inflation led foreign institutions (FIIs) to sell the Indian currency, pushing it to an all-time low of 54.30 against the US Dollar in the December.
The RBI refused to deploy India’s foreign exchange reserves to curtail this slide, as it was not a phenomenon that monetary action could fix alone. So RBI used alternative methods to curb speculation on the Rupee. It banned firms to enter multiple forward contracts to cover a single foreign currency transaction, and also eased rules for companies to raise offshore debt. It also raised the interest rates payable on deposits made by Non-Resident Indians. Also in December, India and Japan signed a $ 15 billion currency swap agreement. The RBI has pledged to keep a close eye on Rupee levels throughout 2012 as a weak rupee would further hurt imports, and on the flipside, exports won’t benefit much either owing to a global slowdown. In fact, firms that had resorted to foreign-currency debt in the form of External Commercial Borrowings, or ECBs (against a backdrop of rising interest rates in India), had to face tremendous pressure servicing that debt with the Rupee at such depressed levels. All in all, a weak currency would hence only add more inflationary pressure on the Indian economy.
Dominated by negative news-flow, such as the FDI in Retail debacle, or missed Divestment targets, criticisms of Policy Paralysis, failure of introducing GST, etc., 2011 was a year to forget for several investors, business leaders, and parliamentarians alike. So as we enter 2012, many “experts” will be hoping for the Union Budget in March to introduce crucial economic reforms. However, the challenges now are more complicated than they have been in recent years. Too much emphasis has been given to the role of RBI’s monetary policy, discounting the importance of the Finance Ministry (Fiscal Policy) in driving the economy. Personally, I expect FY13 to be much choppier than last year, and expect things to get much worse before getting any better. Considering the nature of coalition politics in India, any reform announced during the budget would come as a surprise, albeit a positive one.

19 Dec 2011

FDI in Indian Retail II


In my previous post on FDI in Retail, I kept the focus limited to numbers & stats, mostly formulated by consultancy firms. The people behind those projections happen to be some of the best brains in our country (handpicked by their employers at IIMs or Ivy League universities). So their analysis in my opinion carries more reliability than most government officials, who are either uneducated (I did not use the word illiterate because the definition of a ‘literate’ in this country is laughable) or too ignorant, or have vested interests (the most probable case). If questioned about their stance on FDI, or asked to explain that stance, they get agitated but fail to provide even one plausible implication of their stance. Sad but true!

So far, the critics of FDI have given reasons along the lines of the following:
  • Kirana shops will close. International sourcing will destroy Indian MSMEs too. This will cause unemployment.
  • Farmers will get exploited.
  • International firms (with deep pockets) will form monopolies and manipulate prices. Hence, the consumers will also be exploited.
  • The Gandhi family wants to bring in FDI to benefit their “foreign cronies”
  • The manner of the policy announcement was “inappropriate” since the Congress did not do adequate “consultations” with the allies and opposition parties. 


However, if anything, these claims have been nothing but populist in nature and their ruckus so far has gained them hefty support from the poorly educated vote-bank, which is not expected to know any better. Some political parties and their supporters seem to be too preoccupied with the Luddite Fallacy, which simply put, is a belief that labor-saving technologies will cause unemployment. As you can tell, the problem with this is that nobody (neither individual nor nation) can progress, let alone innovate, holding such a premise as core value. So it comes as little surprise that when the Prime Minister made an executive decision, the opposition created a pandemonium, both in parliament and on the streets, and forced the government to suspend the proposal in the name of democracy.

Now then, I doubt I need to remind you of how Protectionism hurts the economy of the country that imposes it. Not only does it disincentivize competitiveness and specialization, thereby deterring potential exports, but it also supports incompetent businesses. One does not need to look too far to validate this as our own history offers enough pointers. Businesses that were protected from foreign competition eventually got complacent and did not bother to innovate to stay competitive. Such complacency sets in to all businesses that are protected as they do not feel threatened by competition and hence they become exploitative in nature themselves. I’m sure you can think of a few such businesses yourself. Personally, I am an advocate of the notion that competition brings out the best of any business, and those that get wiped out were obviously not competent enough. Organized retail – though currently only 6% of the total retail market – is here to stay and is expected to rise to 21% over the coming years. This means that the Kirana shops will not be facing competition for the 1st time.


In fact, judging by the VAT collections of the kirana stores between 2000 and 2010, which increased from Rs 3300 Cr to Rs 8300 Cr, one can only say that they have done well to hold their place despite the emergence of organized retailers (See graph). If anything, this would be another opportunity for them to cement their place in their neighborhoods. How? Consider this example of this shopkeeper in Delhi :

In 2009:
  • 500 sq feet store with typical kirana layout and design, open 16 hours daily
  • Had 4 employees (2 sons and 2 hired), and total of 448 employee hours every week (4 employees x 16 hours x 7 days)

In 2010, it was time to innovate (& renovate) :
  • Repainted walls, added 3 shelf racks, 2 fridges, and 1 air-conditioner
  • From Kirana format, it migrated to the self-service format
  • Renovation Cost = Rs 90,000 & Time = 45 days

In 2011, post renovation results:
  • 80% growth in sales
  • Employee hours reduced by 25% to 336 hours per week (2 employees could now work part-time 8 hour shifts)

This is a true story of a kirana shop embracing change, modernizing, and as a result, enjoying higher sales and lower costs, which translated to better profit margins. An average kirana shopkeeper (working in meager conditions) does not take home more than Rs 10,000 – 12,000 per month. So when his sales nearly doubled (for the sake of simplicity, let’s assume that the decline in wage-bill was equal to the rise in his electricity bill), his improved profits (and work environment) could go a long way in improving his livelihood. He could potentially scale up his purchases and hence improve his bargaining power; perhaps he could eliminate an intermediary, thereby further lowering his costs. What he actually does with that extra income could be anybody’s guess, but the key takeaway here is that competition brought the best out of him. Had there been no pressure from bigger and fancier stores opening around Delhi, he might never have bothered doing what he did.

Next, I want to draw your attention to the graph. It is a comparison of the rise in CPI (Consumer Price Index) in 6 cities between 2000 and 2010. As you can see, cities with more organized retail – Mumbai, Hyderabad and Delhi – had faced less inflation (measured by change in CPI) compared to other cities – Amritsar, Kanpur and Nagpur – where retail is relatively less organized. This is essentially because organized retailers have bargaining power that individual small shops don’t. And while the scale of our domestic organized retailers is not very large, it still managed to keep inflation significantly low. Now, if, or when, the government’s better sense prevails and FDI is finally permitted, the inflation will be even lower.


In my last post, I already highlighted how organized retail (with FDI) would bring superior scalability, eliminate unnecessary intermediaries, and establish a high quality back-end infrastructure of international benchmarks. One thing I would like to add to that list is that it would lower Shrinkage Cost, which is the cost of slippages such as employee thefts, vendor faults, administrative errors, shoplifting, etc. This, in case of India is as high as 4% of total sales (read: losses) compared to a benchmark of only 1.5% globally. Furthermore, According to Technopak, while Indian retailers currently hold their inventory for an average of 128 days, their foreign counterparts hold their inventory only for 38 days because of their ability to source directly from the producers. That statistic alone shows that their efficiency in inventory management is 300% higher. Statistics aside, foreign retailers will also instill professionalism in their dealings (paying the suppliers on time, no worker exploitation), and inculcate a strong work culture benchmarking best practices.

According to the DIPP, India produces about 180 million tons of fruits and vegetables, but has a cold storage capacity of only 23.6 million tons (5,386 standalone units). That is a deficit of about 87%, and according to CRICIL causes losses worth a whopping Rs 10,000 Cr annually. What’s worse is that more than 80% of that cold storage capacity is wasted on potatoes alone. Sadly, the fact of the matter is that currently, India is relying on infrastructure that is outdated by decades. It does not have a proper logistics network, but just a number of warehouses and transport offices scattered across the country. As the country (and its citizens) develops, it is going to need adequate infrastructure in place to facilitate its growth ambitions. The Planning Commission of India estimates that India needs an investment of Rs 60,000 Cr (about $13 billion) in its agricultural infrastructure alone. Only way that this is possible is if the government puts its politics aside and allows FDI in multi-brand retail.

Let me give a scenario where the Indian retail industry is protected and FDI is not permitted. The outcomes of this would be actually very undesirable. Lets take a look:
  • No Foreign Capital Inflow – With no inflow of foreign capital, the Rupee will remain weak for the foreseeable future and our expensive imports will continue to exert inflationary pressures.
  • No Technological Breakthrough – This, in my opinion, is more important that inflows of capital. I already spoke about these so I will not repeat myself, but I will remind you that the value that the likes of Wal-Mart and Tesco will bring in technological knowhow would be priceless. While we tout about our software exports, it is crucial to realize that we lag far behind the world in actually adopting some of those technologies.
  • Slower Job Creation – Since there will be no FDI, the growth in organized retail will come from our incumbent companies. But with business confidence so low, corporate balance so leveraged and the cost of credit (interest rates) so high, the growth is going to be much slower. This means that fewer jobs will be created than otherwise.
  • No Infrastructure Development – I think it’s about time we smell the coffee and admit that the Government lacks the ability (and perhaps political will too) to eliminate infrastructure bottlenecks that cost us over 2% of our GDP every year. For those who think I’m being over-cynical in this regard, just compare the quality of roads that have been built in the last decade (try to focus on the damage) with the quality of infrastructure built over 60 years ago and is now probably declared heritage property (compare the damage). The potholes, the railway accidents, the filthy streets, and the overall neglect speak for themselves.


By now, I’m sure you get the picture. However, before I conclude, I would like to make one suggestion on this policy. That is to increase the 30% local MSMEs sourcing requirement to 50%. This is because giant organized retailers source about 30-40 percent locally anyway in order to achieve cost-efficiency. Furthermore, it makes little business sense in trying to sell grainy Chinese rice to an Indian basmati-loving consumer base. Hence, by imposing a local sourcing target of only 30%, the government is not doing any favors for Indian MSMEs. Secondly, I hope the Indian government doubles the definition of MSMEs from an asset base of Rs 5cr ($1million) to Rs 10Cr as overtime, in order to be able to meet the large demands of the retailers, the MSMEs will need to increase capacity and will then no longer remain in that MSME category since their asset base might exceed Rs 5 Cr. Moreover, opening up the multi-brand retail markets to foreign firms will also require India to rethink about the legal infrastructure – something else that India needs desperately since our legal system is very outdated. Issues such as taxation, labor laws, procurement laws, and food and safety standards will all have to be revisited. A nation with an economy developing at such rate needs a legal system progressive enough to match it strides.

Finally, the Indian economy grew at an aggregate of 105% between 2005 and 2011. Today, rural income is rising, and consequentially rural spending (demand) is rising. The rural demands in the same period (2005-11) grew by 35% for milk, 70% for vegetables, and another 70% for packaged and processed food items. This further shows that not only are kirana shops going to stay, but also that removal of intermediaries will give the farmers and other rural communities more disposable income will then improve the standard of living, and hence the social fabric of those communities (a positive externality). This however has one more implication. As these rural incomes rise, and the villages and rural areas are developed, new towns will be formed. Furthermore, there is already intense migrating from villages to big cities already. This will then make the procurement and logistics of food across the country a very complex process. Hence, in order to avoid chaos, adequate investments and careful planning needs to be put in place before it gets too late. FDI will bring in both the resources needed (capital and expertise) to do just that, and should therefore be seen as a boon to our supply chain, and hence, to our infrastructure thus the entire economy.


Concluding this post, I would only say that FDI in retail is something that India needs (almost desperately) and hence should embraced with both arms instead of resisting. It could add about 4-5% to our GDP every year. Take a look at the chart above. It shows the breakdown of the costs a consumer pays for tomatoes. The farmer gets only 30% of the final price, the retailer takes 21%, and the remaining 49% is distributed among other intermediaries. Considering that organized retailers could source directly from the farmers, how much value do you now think the intermediaries add?

A study by ICRIER (Indian Council for Research on International Economic Relations) came up with some interesting insight.

  • The average distance from a consumer is 1.1km for a kirana store, but 2.6km for an organized retailer. In fact, 64% of the smaller kirana stores well less than 500 meters away.
  • 35% of the kirana stores recognize their regular customers and give them credit. In fact, credit sales are makeup 22% of their total sales. These kiranas also know their customers’ tastes and can follow the changing tastes.  

Take a look at the graph below. It shows what FDI Liberation in the Retail Sector did for China. Why China? Because of the similar population size, and traditional agricultural economic roots. But the similarities end there. Anyways, the India-China comparison can be left for another day. For now, I've only brought this up to raise a simple question. Can liberating FDI do the same for Indian Retail sector? 


Let me give you an example. You realize that you are out of bread or eggs one morning. How would you make that purchase? Would you go to the big retailer in your city, or just downstairs to the nearest kirana store? What if you realized you did not have change? Or were crunched on time? In case you didn’t realize where I am going with this, I’m only trying to remind you that your neighborhood kiranas have a place of their own in the Indian retail landscape and the likes of Wal-Mart, Tesco, Carrrefour SA, etc. cannot take their place. If anything, it is 7-eleven that we should be worried about!