Showing posts with label government. Show all posts

18 Mar 2012

India's Union Budget FY 2013


The run-up to the Union Budget has seen a plethora of ‘experts’ (bankers, corporate executives, investors, economists, journalists, etc.) voicing their opinion of what the Union Budget FY2013 should look like. The Union Budget is probably the most hyped up event in the economic calendar. From being a simple event of the government declaring the profit and loss account of the public finances, it has undergone a metamorphosis, whereby the government now provides a snapshot of the nitty-gritties of the economy, policy ingredients, and guidance for the next fiscal year. Nobody gains from this parliamentary Budget session as much as the media. In fact, judging by the past few years, the Budget has been more of the TRP (Television Rating Point) event than a GDP (Gross Domestic Product) event.

 
Budget Day in India is somewhat of a close follower of the British counterpart. For many years in Britain, the Chancellor of the Exchequer ceremonially enters the House of Commons with a Victorian-era ‘budget box’ briefcase. In similar fashion, Indian Finance Minister Pranab Mukherjee clutched his red leather briefcase as he entered the Indian Parliament building. Mr. Mukherjee presented India’s 81st annual Budget on March 16th; Individually, it was his seventh, the second highest by any Finance Minister in India. Several ‘experts’ were hoping the budget would introduce the much-awaited reforms that would spur economic growth, and bring back the investor confidence. The key reforms anticipated by the markets included:
  1. A revamp of Tax-structure by introducing Goods and Service Tax (GST) and a Direct Tax Code (DTC)
  2. Allowing Foreign Direct Investment (FDI) in sectors such as Aviation, Retail, and Insurance
  3. Trimming the fiscal deficit
  4. Removing infrastructure bottlenecks
  5. Breakup of the state-run Coal monopoly
  6. Cutting back on subsidies (Fuel, Fertilizer, and Food)
  7. Maybe even some tax relief for the middle class

However, one doesn’t need to be a genius to realize that making everybody happy was impossible. The FY-2013 Budget, like most of its predecessors, stuck to the age-old trend of taxing consumption, raising taxes for existing taxpayers to pay for the handouts given to the impoverished, bail-out ailing sectors, and optimistically talk about reforms to come. The emphasis was on Inclusive Growth, with increased spending on agriculture, healthcare, and education. Little wonder that his choice of literary quote was from Hamlet: “I must be cruel, only to be kind”, compared to Dr. Manmohan Singh citing Victor Hugo in 1991, “a reformed and confident India was an idea whose time had come”.

The FM started his budget speech reminding everyone of the tough global economic environment (high oil prices due to tensions in the Middle East, European Crisis, the usual suspects really). Then he moved on to present India’s economic performance. FY2012 GDP growth rate pegged at 6.9%, compared to 8.4% in the previous year. GDP growth for FY2013 expected to be around 7.6%. Then he moved on to talk about fiscal consolidation, saying that issues regarding public finance – something that investors and the RBI have been demanding for quite some time now – would be addressed. The fiscal deficit, targeted at 4.6% of the GDP, was likely to be around 5.9% for the year ending March 2012. However, factoring in the states’ deficit, and off-balance sheet items, the overall deficit could touch 9%. He announced the target for next fiscal year to be 5.1% (and below 4% in 3 years), which would be achieved on the back of increased service and excise taxes, and subsidy expenditure reduced to 2% of the GDP (and 1.7% in 3 years) from about 2.7% now. It also set a divestment target of Rs 300 billion for FY2013 compared to its FY2012 target of Rs 400 billion, of which it only managed to raise Rs. 139.1 billion (through an FPO of Power Finance Corp. and a 5% stake auction on Oil &Natural Gas Corp.)

He also tried to excite the financial markets by proposing Qualified Foreign Investors (QFIs) access to Indian Corporate Bond Markets; and incentivize greater participation by retail investors in equity markets through Rajiv Gandhi Equity Savings Scheme, which would give them 50% income-tax deduction upto Rs. 50,000. Then he announced that small investors could e-vote in companies. Obviously their e-vote would not be sufficient to stop the Government from looting PSUs (Remember ONGC?). Furthermore, he lowered the Securities Transaction Tax (STT) to just 0.1%.

Mr. Mukherjee then moved on to talk about the bottlenecks in the economy:
  • Provided Rs 158.88 billion for recapitalization of public sector banks, regional-rural banks, and other financial institutions like National Bank for Agriculture and Rural Development (NABARD)
  • Allowed another Rs. 600 billion worth of tax-free bond issuances to fund infrastructure projects
  • Cut customs duty on imported coal to ensure fuel supply for power generation
  • Directed Coal India to sign long-term Fuel Supply Agreements (FSAs) with Power plants
  • Allowed Airlines to raise more foreign loans (ECBs) for Working Capital
  • Allowed ECBs for Capex Requirements of Infrastructure Projects (more specifically, power projects, roads and highway projects)
  • Set up a Credit Guarantee Trust Fund and allowed ECBs for Low-Cost Housing Projects to address shortage of affordable housing in many cities
  • Provided for Telecom Towers to get viability gap-funding
  • Increased funding for National Rural Health Mission (NRHM) to Rs. 20.8 billion
  • Announced a “White Paper” is being prepared to deal with on black money (illicit funds) stashed both, at home and abroad
  • Increased Defense spending by 17% to Rs. 1.93 trillion
  • Provided Rs. 255.55 billion to the Right to Education, a 21.7% yoy increase, and also proposed setting up a Credit Guarantee Fund for students

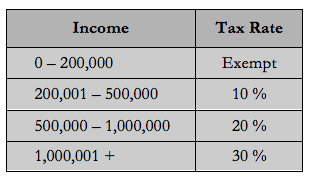
Finally he spoke about Taxes. On personal taxes, he enhanced the basic limit for tax exemption to Rs. 200,000, and expanded the 20% tax slab upto Rs. 1 million. The new tax slabs is illustrated below. Furthermore, there would be no separate tax slabs for women. Interest-income upto Rs. 10,000 from savings account in banks or post offices would now be tax-free. But custom duty on Gold and Platinum were increased (understandably so, to curb gold imports and to channel that money into more productive areas of the economy). Additionally, Sin tax increased on some tobacco products.

 There was no change in corporate tax rates. Broadly, service taxes and general excise duties were hiked to 12%. However, peak excise duty remains unchanged at 10%. This surely would be inflationary as services account for 59% of our GDP. I have compiled a chart to illustrate which goods or services will now cost more and which will cost less.


Overall, Union Budget 2013 was expected to deliver big-bang reforms. But all it had to offer was the traditional mix of more public spending and reshuffled taxes, none of which will be revitalize the stalled engines of economic growth. However, one announcement that was big bang in nature was that of General Anti Avoidance Rules (GAAR), a proposal to amend tax laws to retroactively levy capital gains tax on Indian assets (even on deals that take place abroad by foreign entities). This would apply to transactions as far back as April 1962. It appears that the amendment is principally aimed at taxing Vodafone, but this could well scare off foreign investors – the same people who fund India’s current account deficit; the same people that the Indian Government has been trying to woo.

Brief Background on Vodafone Case:

The British telecom giant bought an Indian operator from Hutchison Telecom of from Hong Kong in an offshore deal in 2007 for $11 billion. However, the Supreme Court of India, in January 2012, ruled that Vodafone should not have to pay a $2.2 billion tax that the Indian government claimed.

Later in the day, Mr. Mukherjee tried to explain that the government was only clarifying the 1962 tax law, and trying to close a loophole that allowed some companies to structure transactions in tax-havens such as Mauritius, purely to avoid paying any capital gains tax. “We are making it very clear that it is the law of the land — this is the intention of the legislature,” he said on NDTV, a news channel.


My Reaction
  
The Union Budget continued with the present Government’s theme of Inclusive Growth. Thankfully however, it refrained from announcing any extremely populist measures, especially considering its poor performance in recent state elections. Instead, it focused on fiscal consolidation. However, no big-ticket reforms were announced either. It seems like whatever additional revenues they’re raising will all be diverted to welfare programs and wasteful subsidies. So in short, our government continues to play Robin Hood.

The government has missed targets before. Furthermore, the last 2 quarters have seen so many revisions that government estimates can no longer be considered a reliable source. There is something really wrong with the way the official statistics are calculated and maintained. Hence pardon my cynicism but I’d take these Budget numbers with a pinch of salt too.

One major takeaway is that the government has missed an opportunity to deliver reforms and jumpstart the productive engines of the economy. I was not expecting the budget to deliver too much, but at least a few reforms were desperately needed. Politics is once again driving the nation at the detriment of economics.

We witnessed this two days ago as well, when a coalition ally Ms. Mamata Bannerjee, populist leader of West Bengal based Trinamool Congress, demanded the Railway Minister (who belongs to her own party) to be fired. 


His crime? Proposing a fractional rise in rail fares to modernize Indian Railways and improve its safety and hygiene. The rail budget was forward-looking, and the fare-hike was very modest, ranging from 2p – 30p per kilometer (or 0.04 – 0.6 cents per km); the fares had not been revised since 8 years. But by proposing this, Rail Minister Mr. Dinesh Trivedi had apparently “gone against the Trinamool Congress Party’s DNA” and that was unacceptable. Imagine their reaction if the government proposed privatizing the railways.

With such obstructing allies, it would be near impossible for the Congress to carry out any significant reforms even if they had a stomach for them. Another problem is that India Inc is a spoilt bunch that loves to sulk; hence business and investment climate will not improve until some policy action from the government. This budget failed to do that. The measures announced were marginal at best. It didn’t help RBI either. The central bank is terrified that inflation would pick up again, reflecting a host of supply-side constraints ranging from agricultural supply chain to inadequate infrastructure.

So what should the Budget have focused on? Even taking baby-steps, but in the right direction, can go a long way to fixing things. In addition to all that Mr. Finance Minister announced, he should have formed a Priority Group to maneuver the following:


  1. Raise diesel prices, incrementally and quietly, but offset that by matching cuts in the tax on diesel. That way, the fiscal hole starts getting plugged, and the consumers don’t feel much of a pinch.
  2. Set-up a facility to fast-track land acquisition and environmental clearances. This would kick-start the implementation of stalled projects, which would create employment along with boosting infrastructure, and housing markets, financial markets, and business sentiment – and all this without investing a single new penny.
  3. Present a draft on GST and DTC, outlining how the overall economy (include every stakeholder) would benefit from it. Start discussions with an established deadline for the rollout.
  4. As of now, India has only 790 diplomats and ambassadors, compared to about 3,000 in Brazil, over 6,000 in China, and well over 20,000 in America. While this may not have much of a direct impact on Indian’s finances (except their payrolls), it does increase India’s presence in different nations. This not only helps in economic ties, but also strategic ties. For a nation trying to strengthen its global footprint, India is severely under-represented on a diplomatic level.

In a separate post, I would like to share 2 open letters addressed to Finance Minister Pranab Mukherjee in response to his budget announcement. They sum up pretty well how some segments of the economy will be affected. A transcript of his BS (I mean Budget Speech) can be found here:

4 Mar 2012

The ONGC Divestment Debacle

Imagine a situation where you are about to buy a product, which costs Rs 100, and the seller is desperate to sell it off. However he is selling it at Rs 120, despite the product having several plaguing issues. Would you still buy it, knowing that the seller is so desperate to sell this product that it may well sell it for Rs 80 a few weeks later? 

I wouldn’t.

Something similar happened at the ONGC’s (Oil and Natural Gas Corp Ltd) share auction on Thursday, March 1st. For the benefit of some readers, let me start with the backdrop. In the last Union Budget, the government had planned to sell a stake in several state-owned companies, aiming to raise Rs 400 billion, but unfavorable market conditions prevented them from doing so. The only stake-sale that went through successfully was an FPO (Follow on Public Offer) of Power Finance Corp., which fetched the government Rs 11.45 Billion. Simply put, the government only managed to achieve 2.9% of its divestment target for the year. Furthermore, the economic slowdown resulted in tax revenues falling short of expectations. But its expenditure bill on the multiple welfare schemes only ballooned. Hence, hard-pressed for funds, and with the fiscal deficit target getting topped already in 10 months ending January, the government made a desperate attempt to sell some stake in ONGC Ltd through a share auction (the Indian Government seems obsessed about auctions) just weeks before this year’s Union Budget.


The government’s frantic attempt to narrow the budget deficit through an untested divestment method was near disastrous. Up for auction were 428 million shares, at a floor price of Rs 290 per share; this equated to a 5% stake in the nation’s biggest energy explorer, valued at Rs 124 billion. The auction started at 9:15 am, but the lukewarm response was causing concerns among officials and merchant bankers alike. Until 3:20 pm, 10 minutes before the bidding closed, only 14.3 million shares were bid for, which is less than 3.4% of the total offer. To add to the theatrics, the websites of the two main exchanges, Bombay Stock Exchange (BSE) and National Stock Exchange (NSE), stopped updating the bidding activity on their respective websites at 3:20 pm.

Then, in typical Bollywood fashion, the last 10 minutes saw bids for 406 million shares, led by other state-owned entities such as State Bank of India (SBI) and Life Insurance Corp (LIC). Seven hours later, at 10:30pm, Government officials confirmed that the final demand from investors was for 420.3 million shares i.e. 98% of the total offer, and the average price received was Rs 303.67 per share, which was a 4.7% premium on the floor price of Rs 290. The total amount raised was Rs 127.67 billion, of which over 110 billion was coughed out by LIC alone, roughly 87% of the total amount. While the reason behind LIC’s last minute endeavor may be open for debate, the 377 million shares it bought increase its total stake in ONGC to 9.48%.


All said and done, the government only has itself to blame for the debacle. It had not put in adequate work to ensure that the auction process went through without any hiccups. Instead, it rushed through it, aiming to raise some quick cash, and hoping to show a lower fiscal deficit number in its Budget session of the Parliament, due in 2 weeks. However, now that the Divestment Department has established that the auction results were satisfying, and that an auction would be the method of choice for further divestments hence forth, the government can take away some valuable lessons from this episode.

The Price – Setting the floor price for the auction at Rs 290 per share was the government’s first mistake. Usually, when a firm tries to sell a stake to public, be it in the form of an IPO or an FPO (or an auction as in this case), they issue the shares at a discount. This is attractive, especially for the retail investors as it leaves some money on the table for them by giving them an opportunity to sell the stock in the secondary markets. When the floor price of Rs 290 was formally announced on Feb 29th, it was at a 1.1% discount from the previous day’s closing price of 293.2.

ONGC Shares, up 14% in 2012 - A misleading benchmark perhaps?

However, what the government (or their advisors) failed to factor in was the wave of liquidity around the world in the last 2 months, which saw foreign investors pour in $7.2 billion (Rs 360 billion) in Indian equity markets, and another $4.8 billion (Rs 240 billion) in the debt markets. Such large inflows caused the ONGC stock to climb 14%. Hence, a more appropriate price would have been somewhere between Rs 260 - 270, the average price in the last few months, thereby offering an attractive discount from the previous trading day’s closing price. Just for the record, the share price as I write this piece is Rs 283 i.e. Rs 7 lost on every share from the auction’s floor price overnight. I wonder how LIC feels about its loss.

The Risks – Another reason why it would have been more prudent on the government’s part to auction at a discount is the operational risk underlying ONGC. In any economy, the nation’s largest energy explorer would be the darling of the investors. However, the case is slightly different in India; on one hand, over 80% of its oil is imported, but on the other hand, the government subsidizes the price of fuel. The problem (not to mention the current account deficit) for investors is that ONGC, being a state-run company, is forced to share a portion of the government’s subsidy burden. In fact recently, the government increased ONGC’s share of burden, and with oil prices edging higher (already above $125 per barrel), chances are that this ratio will increase much further.
 
In addition to the impact on costs and earnings, investors have also been worried about the ad hoc nature of the subsidy sharing arrangement. According to the Economic Times, the company’s subsidy burden for the first 2 quarters of FY12 was close to 30% of the oil marketing companies’ under-recoveries. However, in the third quarter (ending December 2011), the methodology was changed and the burden was calculated to be $56 per barrel, rising from 33% to 38% for the entire 9-month period, April - December. As a result, there was a steep rise of 47% in burden in a single quarter, and no assurances that the methodology wouldn’t change again in the future. Hence, with such uncertainty over issues that have a direct bearing on its profitability, a floor price of Rs 290 was totally unjustified vis-à-vis the underlying risk.

The Timing – The government has been teasing the markets with the idea of an ONGC FPO since December 2010. While the offering was postponed several times, a mere discussion about it stagnated the share price as investors were anticipating a discounted offering. So much so that the stock did not even react to developments such as a bonus issue and a stock split (both of which would otherwise cause a significant rally) in February 2011.

However, when the time finally did come, the government rushed through the process, in order to fill its coffers before the financial year ended. They neither gave themselves and their bankers enough time to market the auction, nor did they give the markets enough time to arrange liquidity to participate. The auction was held barely 48 hours after an official announcement. For a market where the average IPO size ranges between Rs 30 billion to Rs 50 billion, a much greater effort was required by brokers and investment bankers to sell an auction worth Rs 124 billion. Therefore, the government should have been more diligent and given themselves and the market about 8-10 days to prepare for the auction. Alternatively, they could have carried it out in multiple steps, for example, 4 auctions of Rs 30 billion each. This would have calmed some jittery nerves among investors, who fundamentally remain very bearish and indecisive due to several domestic and international overhangs (European Crisis, Slowing GDP, etc.)

All in all, I can see why the government tried to rush through the auction. I can also see why they set the floor price at Rs 290. In the grand scheme of things, ONGC is still undervalued at Rs 290; therefore longer-term investors wouldn’t mind the price too much. However, it is important that the lessons are learnt from this experience. I am convinced that we are living in a world where sentiments control stock prices (at least in the short term), and government interventions drive the economy. Hence the single most critical factor one should evaluate is the underlying risk – risk of a bad investment; risk of mismanaging a stake sale; risk of making a wrong decision. Come to think about it, it’s a life lesson isn’t it?

Update: According to news reports, the decline in ONGC’s share price over the last 2 days (post auction) has cost LIC Rs 9 billion.

Ouch !


12 Feb 2012

The Hullabaloo over 2G Licenses

Last year, Time Magazine listed the Indian Telecom Scam 2nd (after the Watergate Scandal) in the “Top 10 Abuses of Power” list. Considering that it has been making headlines since 2010, I suppose most of you know the details of the scandal. However, for those just tuning in, I thought I’d do a post featuring the 2G Licenses and Spectrum Scandal.

What happened?

In 2008, A. Raja, the erstwhile Minister for Communication and IT, decided to allocate 2G licenses and spectrum to several telecom companies, some of whom did not meet the basic requirements to be granted a license. Furthermore, he sold the licenses and spectrum at apparently throwaway prices, causing the exchequer to suffer from revenue losses, estimated up to Rs. 1.76 Trillion ($ 35.2 Billion) according to the Comptroller and Auditor General of India. Interestingly, Kapil Sibal, the incumbent minister of Communication and IT, dismissed the estimates calling them meaningless “notional” figures. Either way, this led to several new players entering the market, and the increased competition (read: price wars) meant lower tariffs for users, and squeezed the profitability of the incumbent players. 


The matter was mute for a couple years of until 2010, when during the 3G license and spectrum auctions, the government realized the amount it had lost in 2008. This incident of poor governance was termed as another scam by our particularly hardworking media. After much political ruckus, the Supreme Court of India declared the allotment as “unconstitutional and arbitrary” and cancelled all the 122 licenses issued by A. Raja. According to the Apex court’s judgment, A. Raja “wanted to favor some companies at the cost of the public exchequer" and "virtually gifted away important national asset" It is worth noting that the Telecom Policy does not have any specific provision for the licenses or spectrum to be auctioned off, and it was only in 2010 that an auction process was deemed to be the most appropriate method of allocating national resources.

Cancelled Licenses and Affected Parties

 
These firms, especially the foreign players, have complained that the Supreme Court ruling disregards the interests of the business community. Furthermore, it is unfair as it makes businesses suffer for what is in essence the Government’s gaffe.  They also said that such moves would make foreign investors hesitant and cautious against investing in India, and this would hurt the nation in the long term.

So what are the implications?

The cancellation of the 122 licenses will affect close to 45 million people around the country (roughly 5% of the total active user base) who will see their services go off. However, the court has given the companies 4 months, so the users will have some time to switch to a different service provider. As for the companies, they are left with 3 options. First, they can go to court and appeal against the verdict (a very lengthy and expensive undertaking). Alternatively, they could bid for the licenses and spectrum (whenever the auctions happen). Or finally, they could exit the Indian telecom market altogether. As for the incumbent players such as Vodafone and AirTel, it is an opportunity to increase their subscriber base, and also a chance to bid for more spectrum. The sector overall will hence see some much needed consolidation, and with competitive pressure reduced now, the unsustainable price-wars can end and the profitability of the firms would increase too.

Personal Take

At just point, I would like to highlight a couple of points, and let you assess the event at your own terms.

Firstly, If 2G spectrum was to be auctioned (like 3G was, and 4G seemingly will be), the government would get more revenues (only to give out more subsidies in my opinion). But would the tariffs be as low as they are? Would your milkman, driver, domestic helper, fruit vendor, etc. all be able to afford it? Would your life be more convenient or less if that was the case?

Secondly, since the spectrum was allocated on a “First Come First Serve” basis instead of an auction, many new players were granted license and spectrum. As a result, incumbent players such as Vodafone and Airtel who have a larger subscriber base were left with too little spectrum to work with while the newer players who were unable to build a sizable subscriber base were sitting idle on precious resource. So this not only prevents the players from achieving economies of scale, but it also translates to poor quality of network coverage for the 800 million mobile phone users across the country.

Thirdly, the scam has further tainted the image of the Government. However, one should really take a step back, and think if this was really as scandalous a misdemeanor as it seems? After all, it did make mobile usage more affordable to the masses. Would 3G (which was auctioned to service providers for Rs. 670 billion or $ 13.4 Billion) be able to achieve the same reach in India’s price elastic telecom market?

Finally, considering as telecommunication and connectivity as a vital infrastructure of the nation, it was an industry that grew at an exponential pace for some time, but that growth has now halted. Little room to expand due to over-competition has led to unsustainable business models. Hence, some consolidation could do wonders for both, consumers as well as the businesses.

The 2G licenses of 2008 were issued at 2001 prices, on a first come first serve basis rather than an auction.  

So, at this point, would you call it a scam or a blunder ?

Corruption or mere Inefficiency ?


I will let you decide for yourself . . .

3 Feb 2012

What the Indian Government can learn from Steve Jobs


Recently, stories surfaced that Steve Jobs had designed the iPad for the first time way back in 1999, and the first iPhone all the way back in 1983. If Ray Hammond, who wrote the world’s first guide to e-commerce “The Online Handbook” more than 2 decades ago, is to be believed, Jobs had already conceptualized the iPhone, iPad, even Siri, as early as in 1983. Such stories only make one wonder why were such brilliant innovations locked-up for so long? If Steve Jobs had already understood that the future was about combining computing with mobility, why did he wait for over a decade to launch it commercially?

In 1998, a year after re-joining the company he co-founded (he resigned after a power-struggle between him and CEO John Sculley in 1985), he famously said that he was “going to wait for the next big thing” when asked by Richard Rummelton about his future plans for Apple. The key here is not just patience; as important as it is, it is pointless without preparation. Upon his comeback, in addition to doing the textbook stuff such as reducing inventory and moving production offshore, he also discontinued several product lines (from 15 desktop models to just 1), eliminated peripherals, and fired many engineers. The goal was to save Apple from the brink of bankruptcy, and his way of doing it was to not insert itself into a market already saturated by IBM and Microsoft (desktop computing), but by dominating new markets altogether (iPods, iPhone, & iPad).

In his sunset years, Steve Jobs had become a global icon, inspiring everybody – CEOs, entrepreneurs, engineers, designers, consumers, and even students who weren’t sure yet. So much so that in November 2009, Fortune Magazine named him CEO of the Decade. So, what does the Indian government have to do with all this? Not much to be honest; but there are a few lessons that they can take-away; lessons of vision, opportunity, quality, control, patience and preparation. 
  1. Vision – Steve Jobs’ vision needs no further testimony than the fact that the popularity of Apple products have made the consumer electronics giant one of the world’s largest public company with close to $100B in cash reserves alone (more than many national treasures). He knew the future was about the marriage of computing & mobility. So he envisioned tablets before anyone else. He was the first to obsolete the use of floppy disks in 1998. He was also single-handedly responsible for Adobe systems to discontinue Flash (the platform that most games, YouTube, Skype, etc. are based on) about 18 months after he publicly espoused HTML5 in an open letter in 2010, saying that it was faster and more efficient in memory consumption.


  2. Opportunist – In an interview to Wired Magazine, Jobs once said “Creativity is just connecting things.” He did not create anything new; he did however synthesize things well. Macintosh, Apple’s popular personal computer was essentially Apple II (which by the way was single-handedly created by co-founder Steve Wozniak) plus a Graphical User Interface (created by Xerox) and a mouse. There were already numerous portable media players in the market before Apple launched iPod, and there were already several smartphones before the iPhone, and tablets before iPad. However, Jobs realized that it was time Apple, on the back of its product design competency, forayed into those markets. Soon after, Apple turned into the new benchmark in the consumer electronics sector, from just a niche computer seller before.

  3. Quality– Jobs was well renowned to be an abrasive & ruthless manager. According to his biographer Walter Isaacson, his cruelty was a product of his quest for perfection in everything he did, be it building Apple computers, or a fence with his father. Furthermore, he wanted to be around only such people who also demanded perfection. He therefore took many products off the market when he rejoined Apple if he thought they were not up to his standards of product quality.

  4. Control – For Apple products to be as revolutionary as they have been, compromising on product quality was not an option. To achieve that level of perfection in engineering and design, Steve Jobs tightly controlled everything at Apple from the top and had the final say on everything, be it manufacturing processes, design, logistics, or marketing. Such a structure is usually associated with start-ups, where the entrepreneur has to take charge of everything. But Jobs practiced it at Apple until the very end, and made Apple the largest Corporation in USA (surpassing Exxon Mobil) by market capitalization.

  5. Patience – Results are a product of both, the concept and execution. Within the realm of execution, a very crucial element is that of timing. Wonderful ideas can fail because they’re ill-timed. So it was reasonable for Jobs to hold on to his idea until he felt the time to execute had arrived. His priority was not to be the first, but to be the best. The fact that high-growth economies of India, Indonesia, Africa, and China still haven’t impressed him enough to consider as serious markets (his focus remains on the developed countries) is another example of him showing immense patience.

  6. Preparation – Waiting for the right time does not mean one just sits back and malingers, especially when perfection is desired from the final result. So one has to be prepared. Newton was Apple’s first handheld device (PDA) in 1993. But despite groundbreaking design, touchscreen with handwriting-recognition, it was discontinued by Apple (upon Jobs’ return in 1997) as it was (a) ahead of its time, and (b) not perfect. But until the right time came, Apple continued developing the device further (both hardware and software) and when it launched the iPad, it changed the way people consumed digital information or entertainment. Behind this digital revolution, just like any revolution, was years of preparation.


These 6 ingredients were crucial for Apple’s success, and Steve Jobs ensured that he led from the front. This is the lesson that the Indian government needs to learn. While there is no shortage of visionaries among the bureaucrats, the execution and implementation of their farsighted plan remains poor. India’s biggest advantage going forward would be the size of its workforce, and domestic consumer market. However, what many commentators are calling Demographic Dividend can easily turn into a Demographic Disaster if critical issues like Malnutrition, Poor Education, Infrastructure, Healthcare, Employment, and Disciplined Policymaking are not addressed.

As far as Opportunity is concerned, India’s got its fair share. Not too long ago, the Commonwealth Games presented one such opportunity to show the world a promising new India. What it showed instead was how mismanaged and corrupt India was. How the quality of infrastructure was still grossly inadequate, and how poor the quality of planning and execution of this major event had been. Opportunities came again; with the West grappled with a severe economic slump, capital looked to flow to Emerging Markets, and India was once again in the spotlight. This time, it was partisan politics and policy paralysis that was plaguing the country. 

I admit it would not be fair to demand perfection from any government, regardless of their economic might or political ideology. However, what ought to be expected from the Indian government is to show leadership, and responsibility. The economic policies should pro-business rather than welfare-based; giving away freebies and waiving off loans among the poor during the election periods offer no long-term solutions nor do they improve sustained living standards. By developing an entrepreneurial ecosystem, giving tax-incentives, offering legal and bureaucratic assistance, promoting new businesses, allowing them to fail, and start-afresh (does this ring any bells?), the government will be able to not only improve living standards sustainability, but also see India rise in the global value chain, not to mention the other benefits (such as improved capital inflows, tourism, robust economic activity, etc.) that the nation will gain from. Like I said, perfection is not expected, but even small steps in the right direction would do wonders too.

For a nation like India – large, diverse, democratic, but corrupt and underdeveloped – the need for exceptional leadership from its government is even greater. By no means am I suggesting a Socialist system; if anything, I encourage the Free Markets with Minimal Government Interference. However, it would it would be very inefficient to adopt the same top-down control like Steve Jobs. So the government’s role should be that of an administrator and supervisor. Paradoxical as it sounds, the Government needs to play regulator, and yet, moderate regulations at the same time as over-regulation would be counterproductive and slow down economic activity. One way to achieve this is shrewd decentralization (more on this topic in future posts).

This brings us to patience and preparation. After having gone through the “Hindu Rate of Growth” for decades until economic liberation in 1991, our political top brass already has patience aplenty. The youth, in contrast, born in an age of instant gratification, are understandably impatient. Over time, several opportunities will come and go, but the need of the hour is for the two generations can work together and build the nation’s physical and social infrastructure. Without such intense preparation, opportunities like Commonwealth Games will bring more scams instead of praise, and insufficient nutrition and inadequate education make the Government's job of turning India from a welfare-dependent state to empowered nation an unattainable ambition. 


10 Dec 2011

FDI in Indian Retail I


After 2 decades of procrastination, it seemed that India was finally opening up its underdeveloped retail market to Foreign Direct Investment (FDI). The landmark announcement  was  made  on Nov 24th, when  the  Union  Cabinet  cleared the bill allowing 100% FDI in Single-brand retail (think: IKEA, LV, Apple, etc.), up  from 51% as it was until now. The announcement also  included a controversial  decision to allow 51% FDI in Multi-brand retail (think: Wal-Mart, Tesco, Carrefour, etc.).

While FDI in Single-brand retail segment has been welcomed, Multi-brand segment has caused hysteria in the Parliament, and cascaded on to the streets with retail stores across the country closing down for a day in protest against FDI (protesting seems to be the biggest trend of the year 2011). These strikes were organized by wholesale traders’ unions and other middlemen in the retail supply-chain, the biggest losers if the likes of Wal-Mart & Tesco come in. The non-functioning parliament cost the nation Rs. 1.5 Cr (15 million) per day, but the opportunity cost of loss of productivity & the cost of impairment of India’s reputation are anybody’s guess. The Prime Minister’s executive authority has now been questioned too. As his Congress Party pitched the idea to other MPs and citizens citing benefits like job creation and modernization of Indian retail, they did not get any support even from their own allies, let alone the opposition parties. The naysayers’ argument was that FDI in Multi-brand retail would put millions out of smaller shopkeepers (kirana shops) out of business, and also that international giants will form monopolies and exploit farmers.

Why would anyone in their right minds participate in such folly? Is it confusion caused by political noise? Or is it ignorance that’s fueling such dissent? Don’t people know better? Do they lack independent judgment? I think it’s absurd that people protest against something that they would actually benefit from. So in this post, I will share my views on the matter. As you can probably tell already, I not only support it, but also encourage it to be rolled out ASAP. I do think that a few tweaks should be made to the finer print. But before l share my views, let me list down some of the features of what the Government’s proposal says.

Salient features of the Multi-brand Retail FDI :
  1. There has to be a minimum investment of $ 100 million.
  2. 50% of the total investment has to be in back-end infrastructure.
  3. Stores are permitted to open only in cities with a population of at least 1 million (10 Lac) people.
  4. At least 30% of manufactured / processed products must be sourced from Indian MSMEs.
  5. The government retains the right to be the first to source agricultural produce.
  6. The Bill is just an enabler; it is essentially up to individual states to allow or disallow the retailers to open shop.
Salient features of the Single-brand Retail FDI :
  1. Brand must already have presence in other countries too.
  2. 30% mandatory sourcing from Indian MSMEs.
  3. Must be branded during manufacturing.
  4. Investor must be Brand Owner, and not a franchisee or a regional license holder.


At this point, allow me to throw some light on the situation. The backdrop has been that of a global slowdown, with Indian government being in the news for all the wrong reasons, ranging from scams to policy paralysis. With painfully high inflation, stunting economic growth and a weakened Rupee, permitting FDI was the Indian government’s stimulus package. Here’s how. Firstly, it attracts long-term capital into India which is both, less speculative and more productive in nature. Such capital investments in India (by both, international and domestic businesses) had declined recently. Secondly, this move would have brought technological knowhow and spur backward integration in organized retail in India. This would lead to drastic improvements in supply-chain infrastructure, especially in the domain of perishable goods, by replacing intermediaries who do not add any value with those who do. Before you jump to conclude that intermediaries are not being removed, but just replaced, let me explain what I mean. Consider the following numbers:

  • Currently, there are about 5-7 intermediaries between the farmers and the retailers. This causes the price of vegetables and fruits to increase multiple folds. For instance, potatoes cost only Rs. 2/Kg in Nasik, Maharashtra (closer to the farms) but by the time it reaches New Delhi, consumers pay Rs. 18/Kg for it. That is a 9-fold price difference, and neither the farmers, nor the customers benefit from it.
  • About 40-45 % of the perishable food produce gets perishes before even making it to the marketplace. This shows the value-destruction of the current intermediaries.
  • According to rating agency CRICIL, India’s organized retail loses Rs. 10,000 Cr ($ 2 bn) annually due to wastage, mostly of perishable products like fruits, vegetables, fish, meat & poultry. While 15% of these losses occur at the farmland itself, another 25% is lost during transportation.
  • The ratio of traders to actual retailers is 0.001. This means that for every 1000 retailers, there is only 1 trader. So the argument that single stores, or (Kiranas) will shut is flawed, and the number of traders who lose jobs is overhyped too. The intermediaries (about 15,000 currently) won’t be left unemployed; instead, they will get new jobs that actually add value in the supply-chain. Direct sourcing from the farmers can reduce supply-chain costs by 10-15%.
  • About 85% of all farmers own only about 2.5 hectares of land or less. This gives then no bargaining power, and they end up getting exploited by the agents. Also, they are not working on a contract-basis, but on a contact-basis. Hence, they have no defense against current exploitation either. On the other hand, for example, Tata Chemicals helps the farmers working with Trent (contractually of-course) in assessing their land, and recommending the most suitable fertilizers and other technologies that could help farmers get a higher output from their land.
  • According to consultancy firm A.T. Kearney, organized retail is currently only 7% of the $435 billion (approx Rs. 21 Lac Crore) Indian retail market but is expected to rise to 21% within the next few years. Food accounts for 70-80% of this. This is led by a consumption class of 400 million people with rising disposable incomes, and a steady rate of urbanization. 

Considering the above numbers, the case for organized retail is self-imposing. Indian conglomerates such as the Tatas, AV Birla, Reliance, etc have already been trying to strengthen their foothold in the Indian organized retail market. While they and other domestic players like Bharti, Future Group, etc. are already trying to eliminate the intermediaries, their scale of operations is not significant enough to bring about a substantial change in the condition of the farmers, or curb prices on a national scale. Furthermore, they lack adequate experience and technical knowhow in the retail domain to introduce any breakthrough innovations. The international players, on the other hand, can leverage their experience to bring the much needed reforms in the Indian supply-chain network by innovating logistics, introducing cold-storage systems, food-processing, IT systems, etc. 

Thirdly, Micro & Small-Scale Enterprises (MSMEs) will have a direct market to sell to and therefore will reap benefit similar to the farmers. In fact, the challenge for them will be to scale up their operations to meet the demand of these organized retailers. In such a scenario, they too will ramp up production scale and hire more workers. Some might even innovate and adopt newer technologies, thereby generating a larger positive spillover effect in their community.

The fourth benefit of FDI in retail will come in the form of a positive externality of making our workforce more employable. At present, several employers often complain of India’s current workforce lacking several key skills and hence being unemployable. Many workers in the current retail sector will not lose jobs like the politicians have been suggesting, but instead, be hired for their experience & understanding of the Indian consumer, and get trained for the new retail landscape. According to reports from the consultancy firm Boston Consulting Group (BCG), organized retail could right away create about 10 million jobs – 4 million direct and another 6 million indirect jobs. It would generate additional incomes of Rs. 73,000 Cr (approx $14.6 billion), and consumers would save about 1.5 Lac Crore (approx $31.25 billion) annually in their shopping bill. However this is only possible if significant scale is achieved and technology is applied, which is only achievable by allowing FDI in Multi-brand retail. The illustration below shows the current employment generated by Retail trade in some cities. These numbers will only grow post FDI reforms.   

These are just some of the more obvious benefits that we can foresee already, and I am sure there are more too. But there’s more to the retail FDI story than just the numbers I presented. I will do a follow-up post on this topic highlighting the bigger picture, and state my case as to why I feel FDI is going to benefit India. Until then, I leave you with this Illustration which appeared in Hindustan Times, showing how some other countries have opened their doors to FDI in their Retail Industry.