Showing posts with label FDI. Show all posts

18 Mar 2012

India's Union Budget FY 2013


The run-up to the Union Budget has seen a plethora of ‘experts’ (bankers, corporate executives, investors, economists, journalists, etc.) voicing their opinion of what the Union Budget FY2013 should look like. The Union Budget is probably the most hyped up event in the economic calendar. From being a simple event of the government declaring the profit and loss account of the public finances, it has undergone a metamorphosis, whereby the government now provides a snapshot of the nitty-gritties of the economy, policy ingredients, and guidance for the next fiscal year. Nobody gains from this parliamentary Budget session as much as the media. In fact, judging by the past few years, the Budget has been more of the TRP (Television Rating Point) event than a GDP (Gross Domestic Product) event.

 
Budget Day in India is somewhat of a close follower of the British counterpart. For many years in Britain, the Chancellor of the Exchequer ceremonially enters the House of Commons with a Victorian-era ‘budget box’ briefcase. In similar fashion, Indian Finance Minister Pranab Mukherjee clutched his red leather briefcase as he entered the Indian Parliament building. Mr. Mukherjee presented India’s 81st annual Budget on March 16th; Individually, it was his seventh, the second highest by any Finance Minister in India. Several ‘experts’ were hoping the budget would introduce the much-awaited reforms that would spur economic growth, and bring back the investor confidence. The key reforms anticipated by the markets included:
  1. A revamp of Tax-structure by introducing Goods and Service Tax (GST) and a Direct Tax Code (DTC)
  2. Allowing Foreign Direct Investment (FDI) in sectors such as Aviation, Retail, and Insurance
  3. Trimming the fiscal deficit
  4. Removing infrastructure bottlenecks
  5. Breakup of the state-run Coal monopoly
  6. Cutting back on subsidies (Fuel, Fertilizer, and Food)
  7. Maybe even some tax relief for the middle class

However, one doesn’t need to be a genius to realize that making everybody happy was impossible. The FY-2013 Budget, like most of its predecessors, stuck to the age-old trend of taxing consumption, raising taxes for existing taxpayers to pay for the handouts given to the impoverished, bail-out ailing sectors, and optimistically talk about reforms to come. The emphasis was on Inclusive Growth, with increased spending on agriculture, healthcare, and education. Little wonder that his choice of literary quote was from Hamlet: “I must be cruel, only to be kind”, compared to Dr. Manmohan Singh citing Victor Hugo in 1991, “a reformed and confident India was an idea whose time had come”.

The FM started his budget speech reminding everyone of the tough global economic environment (high oil prices due to tensions in the Middle East, European Crisis, the usual suspects really). Then he moved on to present India’s economic performance. FY2012 GDP growth rate pegged at 6.9%, compared to 8.4% in the previous year. GDP growth for FY2013 expected to be around 7.6%. Then he moved on to talk about fiscal consolidation, saying that issues regarding public finance – something that investors and the RBI have been demanding for quite some time now – would be addressed. The fiscal deficit, targeted at 4.6% of the GDP, was likely to be around 5.9% for the year ending March 2012. However, factoring in the states’ deficit, and off-balance sheet items, the overall deficit could touch 9%. He announced the target for next fiscal year to be 5.1% (and below 4% in 3 years), which would be achieved on the back of increased service and excise taxes, and subsidy expenditure reduced to 2% of the GDP (and 1.7% in 3 years) from about 2.7% now. It also set a divestment target of Rs 300 billion for FY2013 compared to its FY2012 target of Rs 400 billion, of which it only managed to raise Rs. 139.1 billion (through an FPO of Power Finance Corp. and a 5% stake auction on Oil &Natural Gas Corp.)

He also tried to excite the financial markets by proposing Qualified Foreign Investors (QFIs) access to Indian Corporate Bond Markets; and incentivize greater participation by retail investors in equity markets through Rajiv Gandhi Equity Savings Scheme, which would give them 50% income-tax deduction upto Rs. 50,000. Then he announced that small investors could e-vote in companies. Obviously their e-vote would not be sufficient to stop the Government from looting PSUs (Remember ONGC?). Furthermore, he lowered the Securities Transaction Tax (STT) to just 0.1%.

Mr. Mukherjee then moved on to talk about the bottlenecks in the economy:
  • Provided Rs 158.88 billion for recapitalization of public sector banks, regional-rural banks, and other financial institutions like National Bank for Agriculture and Rural Development (NABARD)
  • Allowed another Rs. 600 billion worth of tax-free bond issuances to fund infrastructure projects
  • Cut customs duty on imported coal to ensure fuel supply for power generation
  • Directed Coal India to sign long-term Fuel Supply Agreements (FSAs) with Power plants
  • Allowed Airlines to raise more foreign loans (ECBs) for Working Capital
  • Allowed ECBs for Capex Requirements of Infrastructure Projects (more specifically, power projects, roads and highway projects)
  • Set up a Credit Guarantee Trust Fund and allowed ECBs for Low-Cost Housing Projects to address shortage of affordable housing in many cities
  • Provided for Telecom Towers to get viability gap-funding
  • Increased funding for National Rural Health Mission (NRHM) to Rs. 20.8 billion
  • Announced a “White Paper” is being prepared to deal with on black money (illicit funds) stashed both, at home and abroad
  • Increased Defense spending by 17% to Rs. 1.93 trillion
  • Provided Rs. 255.55 billion to the Right to Education, a 21.7% yoy increase, and also proposed setting up a Credit Guarantee Fund for students

Finally he spoke about Taxes. On personal taxes, he enhanced the basic limit for tax exemption to Rs. 200,000, and expanded the 20% tax slab upto Rs. 1 million. The new tax slabs is illustrated below. Furthermore, there would be no separate tax slabs for women. Interest-income upto Rs. 10,000 from savings account in banks or post offices would now be tax-free. But custom duty on Gold and Platinum were increased (understandably so, to curb gold imports and to channel that money into more productive areas of the economy). Additionally, Sin tax increased on some tobacco products.
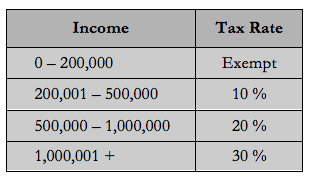

 There was no change in corporate tax rates. Broadly, service taxes and general excise duties were hiked to 12%. However, peak excise duty remains unchanged at 10%. This surely would be inflationary as services account for 59% of our GDP. I have compiled a chart to illustrate which goods or services will now cost more and which will cost less.


Overall, Union Budget 2013 was expected to deliver big-bang reforms. But all it had to offer was the traditional mix of more public spending and reshuffled taxes, none of which will be revitalize the stalled engines of economic growth. However, one announcement that was big bang in nature was that of General Anti Avoidance Rules (GAAR), a proposal to amend tax laws to retroactively levy capital gains tax on Indian assets (even on deals that take place abroad by foreign entities). This would apply to transactions as far back as April 1962. It appears that the amendment is principally aimed at taxing Vodafone, but this could well scare off foreign investors – the same people who fund India’s current account deficit; the same people that the Indian Government has been trying to woo.

Brief Background on Vodafone Case:

The British telecom giant bought an Indian operator from Hutchison Telecom of from Hong Kong in an offshore deal in 2007 for $11 billion. However, the Supreme Court of India, in January 2012, ruled that Vodafone should not have to pay a $2.2 billion tax that the Indian government claimed.

Later in the day, Mr. Mukherjee tried to explain that the government was only clarifying the 1962 tax law, and trying to close a loophole that allowed some companies to structure transactions in tax-havens such as Mauritius, purely to avoid paying any capital gains tax. “We are making it very clear that it is the law of the land — this is the intention of the legislature,” he said on NDTV, a news channel.


My Reaction
  
The Union Budget continued with the present Government’s theme of Inclusive Growth. Thankfully however, it refrained from announcing any extremely populist measures, especially considering its poor performance in recent state elections. Instead, it focused on fiscal consolidation. However, no big-ticket reforms were announced either. It seems like whatever additional revenues they’re raising will all be diverted to welfare programs and wasteful subsidies. So in short, our government continues to play Robin Hood.

The government has missed targets before. Furthermore, the last 2 quarters have seen so many revisions that government estimates can no longer be considered a reliable source. There is something really wrong with the way the official statistics are calculated and maintained. Hence pardon my cynicism but I’d take these Budget numbers with a pinch of salt too.

One major takeaway is that the government has missed an opportunity to deliver reforms and jumpstart the productive engines of the economy. I was not expecting the budget to deliver too much, but at least a few reforms were desperately needed. Politics is once again driving the nation at the detriment of economics.

We witnessed this two days ago as well, when a coalition ally Ms. Mamata Bannerjee, populist leader of West Bengal based Trinamool Congress, demanded the Railway Minister (who belongs to her own party) to be fired. 


His crime? Proposing a fractional rise in rail fares to modernize Indian Railways and improve its safety and hygiene. The rail budget was forward-looking, and the fare-hike was very modest, ranging from 2p – 30p per kilometer (or 0.04 – 0.6 cents per km); the fares had not been revised since 8 years. But by proposing this, Rail Minister Mr. Dinesh Trivedi had apparently “gone against the Trinamool Congress Party’s DNA” and that was unacceptable. Imagine their reaction if the government proposed privatizing the railways.

With such obstructing allies, it would be near impossible for the Congress to carry out any significant reforms even if they had a stomach for them. Another problem is that India Inc is a spoilt bunch that loves to sulk; hence business and investment climate will not improve until some policy action from the government. This budget failed to do that. The measures announced were marginal at best. It didn’t help RBI either. The central bank is terrified that inflation would pick up again, reflecting a host of supply-side constraints ranging from agricultural supply chain to inadequate infrastructure.

So what should the Budget have focused on? Even taking baby-steps, but in the right direction, can go a long way to fixing things. In addition to all that Mr. Finance Minister announced, he should have formed a Priority Group to maneuver the following:


  1. Raise diesel prices, incrementally and quietly, but offset that by matching cuts in the tax on diesel. That way, the fiscal hole starts getting plugged, and the consumers don’t feel much of a pinch.
  2. Set-up a facility to fast-track land acquisition and environmental clearances. This would kick-start the implementation of stalled projects, which would create employment along with boosting infrastructure, and housing markets, financial markets, and business sentiment – and all this without investing a single new penny.
  3. Present a draft on GST and DTC, outlining how the overall economy (include every stakeholder) would benefit from it. Start discussions with an established deadline for the rollout.
  4. As of now, India has only 790 diplomats and ambassadors, compared to about 3,000 in Brazil, over 6,000 in China, and well over 20,000 in America. While this may not have much of a direct impact on Indian’s finances (except their payrolls), it does increase India’s presence in different nations. This not only helps in economic ties, but also strategic ties. For a nation trying to strengthen its global footprint, India is severely under-represented on a diplomatic level.

In a separate post, I would like to share 2 open letters addressed to Finance Minister Pranab Mukherjee in response to his budget announcement. They sum up pretty well how some segments of the economy will be affected. A transcript of his BS (I mean Budget Speech) can be found here:

19 Dec 2011

FDI in Indian Retail II


In my previous post on FDI in Retail, I kept the focus limited to numbers & stats, mostly formulated by consultancy firms. The people behind those projections happen to be some of the best brains in our country (handpicked by their employers at IIMs or Ivy League universities). So their analysis in my opinion carries more reliability than most government officials, who are either uneducated (I did not use the word illiterate because the definition of a ‘literate’ in this country is laughable) or too ignorant, or have vested interests (the most probable case). If questioned about their stance on FDI, or asked to explain that stance, they get agitated but fail to provide even one plausible implication of their stance. Sad but true!

So far, the critics of FDI have given reasons along the lines of the following:
  • Kirana shops will close. International sourcing will destroy Indian MSMEs too. This will cause unemployment.
  • Farmers will get exploited.
  • International firms (with deep pockets) will form monopolies and manipulate prices. Hence, the consumers will also be exploited.
  • The Gandhi family wants to bring in FDI to benefit their “foreign cronies”
  • The manner of the policy announcement was “inappropriate” since the Congress did not do adequate “consultations” with the allies and opposition parties. 


However, if anything, these claims have been nothing but populist in nature and their ruckus so far has gained them hefty support from the poorly educated vote-bank, which is not expected to know any better. Some political parties and their supporters seem to be too preoccupied with the Luddite Fallacy, which simply put, is a belief that labor-saving technologies will cause unemployment. As you can tell, the problem with this is that nobody (neither individual nor nation) can progress, let alone innovate, holding such a premise as core value. So it comes as little surprise that when the Prime Minister made an executive decision, the opposition created a pandemonium, both in parliament and on the streets, and forced the government to suspend the proposal in the name of democracy.

Now then, I doubt I need to remind you of how Protectionism hurts the economy of the country that imposes it. Not only does it disincentivize competitiveness and specialization, thereby deterring potential exports, but it also supports incompetent businesses. One does not need to look too far to validate this as our own history offers enough pointers. Businesses that were protected from foreign competition eventually got complacent and did not bother to innovate to stay competitive. Such complacency sets in to all businesses that are protected as they do not feel threatened by competition and hence they become exploitative in nature themselves. I’m sure you can think of a few such businesses yourself. Personally, I am an advocate of the notion that competition brings out the best of any business, and those that get wiped out were obviously not competent enough. Organized retail – though currently only 6% of the total retail market – is here to stay and is expected to rise to 21% over the coming years. This means that the Kirana shops will not be facing competition for the 1st time.


In fact, judging by the VAT collections of the kirana stores between 2000 and 2010, which increased from Rs 3300 Cr to Rs 8300 Cr, one can only say that they have done well to hold their place despite the emergence of organized retailers (See graph). If anything, this would be another opportunity for them to cement their place in their neighborhoods. How? Consider this example of this shopkeeper in Delhi :

In 2009:
  • 500 sq feet store with typical kirana layout and design, open 16 hours daily
  • Had 4 employees (2 sons and 2 hired), and total of 448 employee hours every week (4 employees x 16 hours x 7 days)

In 2010, it was time to innovate (& renovate) :
  • Repainted walls, added 3 shelf racks, 2 fridges, and 1 air-conditioner
  • From Kirana format, it migrated to the self-service format
  • Renovation Cost = Rs 90,000 & Time = 45 days

In 2011, post renovation results:
  • 80% growth in sales
  • Employee hours reduced by 25% to 336 hours per week (2 employees could now work part-time 8 hour shifts)

This is a true story of a kirana shop embracing change, modernizing, and as a result, enjoying higher sales and lower costs, which translated to better profit margins. An average kirana shopkeeper (working in meager conditions) does not take home more than Rs 10,000 – 12,000 per month. So when his sales nearly doubled (for the sake of simplicity, let’s assume that the decline in wage-bill was equal to the rise in his electricity bill), his improved profits (and work environment) could go a long way in improving his livelihood. He could potentially scale up his purchases and hence improve his bargaining power; perhaps he could eliminate an intermediary, thereby further lowering his costs. What he actually does with that extra income could be anybody’s guess, but the key takeaway here is that competition brought the best out of him. Had there been no pressure from bigger and fancier stores opening around Delhi, he might never have bothered doing what he did.

Next, I want to draw your attention to the graph. It is a comparison of the rise in CPI (Consumer Price Index) in 6 cities between 2000 and 2010. As you can see, cities with more organized retail – Mumbai, Hyderabad and Delhi – had faced less inflation (measured by change in CPI) compared to other cities – Amritsar, Kanpur and Nagpur – where retail is relatively less organized. This is essentially because organized retailers have bargaining power that individual small shops don’t. And while the scale of our domestic organized retailers is not very large, it still managed to keep inflation significantly low. Now, if, or when, the government’s better sense prevails and FDI is finally permitted, the inflation will be even lower.


In my last post, I already highlighted how organized retail (with FDI) would bring superior scalability, eliminate unnecessary intermediaries, and establish a high quality back-end infrastructure of international benchmarks. One thing I would like to add to that list is that it would lower Shrinkage Cost, which is the cost of slippages such as employee thefts, vendor faults, administrative errors, shoplifting, etc. This, in case of India is as high as 4% of total sales (read: losses) compared to a benchmark of only 1.5% globally. Furthermore, According to Technopak, while Indian retailers currently hold their inventory for an average of 128 days, their foreign counterparts hold their inventory only for 38 days because of their ability to source directly from the producers. That statistic alone shows that their efficiency in inventory management is 300% higher. Statistics aside, foreign retailers will also instill professionalism in their dealings (paying the suppliers on time, no worker exploitation), and inculcate a strong work culture benchmarking best practices.

According to the DIPP, India produces about 180 million tons of fruits and vegetables, but has a cold storage capacity of only 23.6 million tons (5,386 standalone units). That is a deficit of about 87%, and according to CRICIL causes losses worth a whopping Rs 10,000 Cr annually. What’s worse is that more than 80% of that cold storage capacity is wasted on potatoes alone. Sadly, the fact of the matter is that currently, India is relying on infrastructure that is outdated by decades. It does not have a proper logistics network, but just a number of warehouses and transport offices scattered across the country. As the country (and its citizens) develops, it is going to need adequate infrastructure in place to facilitate its growth ambitions. The Planning Commission of India estimates that India needs an investment of Rs 60,000 Cr (about $13 billion) in its agricultural infrastructure alone. Only way that this is possible is if the government puts its politics aside and allows FDI in multi-brand retail.

Let me give a scenario where the Indian retail industry is protected and FDI is not permitted. The outcomes of this would be actually very undesirable. Lets take a look:
  • No Foreign Capital Inflow – With no inflow of foreign capital, the Rupee will remain weak for the foreseeable future and our expensive imports will continue to exert inflationary pressures.
  • No Technological Breakthrough – This, in my opinion, is more important that inflows of capital. I already spoke about these so I will not repeat myself, but I will remind you that the value that the likes of Wal-Mart and Tesco will bring in technological knowhow would be priceless. While we tout about our software exports, it is crucial to realize that we lag far behind the world in actually adopting some of those technologies.
  • Slower Job Creation – Since there will be no FDI, the growth in organized retail will come from our incumbent companies. But with business confidence so low, corporate balance so leveraged and the cost of credit (interest rates) so high, the growth is going to be much slower. This means that fewer jobs will be created than otherwise.
  • No Infrastructure Development – I think it’s about time we smell the coffee and admit that the Government lacks the ability (and perhaps political will too) to eliminate infrastructure bottlenecks that cost us over 2% of our GDP every year. For those who think I’m being over-cynical in this regard, just compare the quality of roads that have been built in the last decade (try to focus on the damage) with the quality of infrastructure built over 60 years ago and is now probably declared heritage property (compare the damage). The potholes, the railway accidents, the filthy streets, and the overall neglect speak for themselves.


By now, I’m sure you get the picture. However, before I conclude, I would like to make one suggestion on this policy. That is to increase the 30% local MSMEs sourcing requirement to 50%. This is because giant organized retailers source about 30-40 percent locally anyway in order to achieve cost-efficiency. Furthermore, it makes little business sense in trying to sell grainy Chinese rice to an Indian basmati-loving consumer base. Hence, by imposing a local sourcing target of only 30%, the government is not doing any favors for Indian MSMEs. Secondly, I hope the Indian government doubles the definition of MSMEs from an asset base of Rs 5cr ($1million) to Rs 10Cr as overtime, in order to be able to meet the large demands of the retailers, the MSMEs will need to increase capacity and will then no longer remain in that MSME category since their asset base might exceed Rs 5 Cr. Moreover, opening up the multi-brand retail markets to foreign firms will also require India to rethink about the legal infrastructure – something else that India needs desperately since our legal system is very outdated. Issues such as taxation, labor laws, procurement laws, and food and safety standards will all have to be revisited. A nation with an economy developing at such rate needs a legal system progressive enough to match it strides.

Finally, the Indian economy grew at an aggregate of 105% between 2005 and 2011. Today, rural income is rising, and consequentially rural spending (demand) is rising. The rural demands in the same period (2005-11) grew by 35% for milk, 70% for vegetables, and another 70% for packaged and processed food items. This further shows that not only are kirana shops going to stay, but also that removal of intermediaries will give the farmers and other rural communities more disposable income will then improve the standard of living, and hence the social fabric of those communities (a positive externality). This however has one more implication. As these rural incomes rise, and the villages and rural areas are developed, new towns will be formed. Furthermore, there is already intense migrating from villages to big cities already. This will then make the procurement and logistics of food across the country a very complex process. Hence, in order to avoid chaos, adequate investments and careful planning needs to be put in place before it gets too late. FDI will bring in both the resources needed (capital and expertise) to do just that, and should therefore be seen as a boon to our supply chain, and hence, to our infrastructure thus the entire economy.


Concluding this post, I would only say that FDI in retail is something that India needs (almost desperately) and hence should embraced with both arms instead of resisting. It could add about 4-5% to our GDP every year. Take a look at the chart above. It shows the breakdown of the costs a consumer pays for tomatoes. The farmer gets only 30% of the final price, the retailer takes 21%, and the remaining 49% is distributed among other intermediaries. Considering that organized retailers could source directly from the farmers, how much value do you now think the intermediaries add?

A study by ICRIER (Indian Council for Research on International Economic Relations) came up with some interesting insight.

  • The average distance from a consumer is 1.1km for a kirana store, but 2.6km for an organized retailer. In fact, 64% of the smaller kirana stores well less than 500 meters away.
  • 35% of the kirana stores recognize their regular customers and give them credit. In fact, credit sales are makeup 22% of their total sales. These kiranas also know their customers’ tastes and can follow the changing tastes.  

Take a look at the graph below. It shows what FDI Liberation in the Retail Sector did for China. Why China? Because of the similar population size, and traditional agricultural economic roots. But the similarities end there. Anyways, the India-China comparison can be left for another day. For now, I've only brought this up to raise a simple question. Can liberating FDI do the same for Indian Retail sector? 


Let me give you an example. You realize that you are out of bread or eggs one morning. How would you make that purchase? Would you go to the big retailer in your city, or just downstairs to the nearest kirana store? What if you realized you did not have change? Or were crunched on time? In case you didn’t realize where I am going with this, I’m only trying to remind you that your neighborhood kiranas have a place of their own in the Indian retail landscape and the likes of Wal-Mart, Tesco, Carrrefour SA, etc. cannot take their place. If anything, it is 7-eleven that we should be worried about!

10 Dec 2011

FDI in Indian Retail I


After 2 decades of procrastination, it seemed that India was finally opening up its underdeveloped retail market to Foreign Direct Investment (FDI). The landmark announcement  was  made  on Nov 24th, when  the  Union  Cabinet  cleared the bill allowing 100% FDI in Single-brand retail (think: IKEA, LV, Apple, etc.), up  from 51% as it was until now. The announcement also  included a controversial  decision to allow 51% FDI in Multi-brand retail (think: Wal-Mart, Tesco, Carrefour, etc.).

While FDI in Single-brand retail segment has been welcomed, Multi-brand segment has caused hysteria in the Parliament, and cascaded on to the streets with retail stores across the country closing down for a day in protest against FDI (protesting seems to be the biggest trend of the year 2011). These strikes were organized by wholesale traders’ unions and other middlemen in the retail supply-chain, the biggest losers if the likes of Wal-Mart & Tesco come in. The non-functioning parliament cost the nation Rs. 1.5 Cr (15 million) per day, but the opportunity cost of loss of productivity & the cost of impairment of India’s reputation are anybody’s guess. The Prime Minister’s executive authority has now been questioned too. As his Congress Party pitched the idea to other MPs and citizens citing benefits like job creation and modernization of Indian retail, they did not get any support even from their own allies, let alone the opposition parties. The naysayers’ argument was that FDI in Multi-brand retail would put millions out of smaller shopkeepers (kirana shops) out of business, and also that international giants will form monopolies and exploit farmers.

Why would anyone in their right minds participate in such folly? Is it confusion caused by political noise? Or is it ignorance that’s fueling such dissent? Don’t people know better? Do they lack independent judgment? I think it’s absurd that people protest against something that they would actually benefit from. So in this post, I will share my views on the matter. As you can probably tell already, I not only support it, but also encourage it to be rolled out ASAP. I do think that a few tweaks should be made to the finer print. But before l share my views, let me list down some of the features of what the Government’s proposal says.

Salient features of the Multi-brand Retail FDI :
  1. There has to be a minimum investment of $ 100 million.
  2. 50% of the total investment has to be in back-end infrastructure.
  3. Stores are permitted to open only in cities with a population of at least 1 million (10 Lac) people.
  4. At least 30% of manufactured / processed products must be sourced from Indian MSMEs.
  5. The government retains the right to be the first to source agricultural produce.
  6. The Bill is just an enabler; it is essentially up to individual states to allow or disallow the retailers to open shop.
Salient features of the Single-brand Retail FDI :
  1. Brand must already have presence in other countries too.
  2. 30% mandatory sourcing from Indian MSMEs.
  3. Must be branded during manufacturing.
  4. Investor must be Brand Owner, and not a franchisee or a regional license holder.


At this point, allow me to throw some light on the situation. The backdrop has been that of a global slowdown, with Indian government being in the news for all the wrong reasons, ranging from scams to policy paralysis. With painfully high inflation, stunting economic growth and a weakened Rupee, permitting FDI was the Indian government’s stimulus package. Here’s how. Firstly, it attracts long-term capital into India which is both, less speculative and more productive in nature. Such capital investments in India (by both, international and domestic businesses) had declined recently. Secondly, this move would have brought technological knowhow and spur backward integration in organized retail in India. This would lead to drastic improvements in supply-chain infrastructure, especially in the domain of perishable goods, by replacing intermediaries who do not add any value with those who do. Before you jump to conclude that intermediaries are not being removed, but just replaced, let me explain what I mean. Consider the following numbers:

  • Currently, there are about 5-7 intermediaries between the farmers and the retailers. This causes the price of vegetables and fruits to increase multiple folds. For instance, potatoes cost only Rs. 2/Kg in Nasik, Maharashtra (closer to the farms) but by the time it reaches New Delhi, consumers pay Rs. 18/Kg for it. That is a 9-fold price difference, and neither the farmers, nor the customers benefit from it.
  • About 40-45 % of the perishable food produce gets perishes before even making it to the marketplace. This shows the value-destruction of the current intermediaries.
  • According to rating agency CRICIL, India’s organized retail loses Rs. 10,000 Cr ($ 2 bn) annually due to wastage, mostly of perishable products like fruits, vegetables, fish, meat & poultry. While 15% of these losses occur at the farmland itself, another 25% is lost during transportation.
  • The ratio of traders to actual retailers is 0.001. This means that for every 1000 retailers, there is only 1 trader. So the argument that single stores, or (Kiranas) will shut is flawed, and the number of traders who lose jobs is overhyped too. The intermediaries (about 15,000 currently) won’t be left unemployed; instead, they will get new jobs that actually add value in the supply-chain. Direct sourcing from the farmers can reduce supply-chain costs by 10-15%.
  • About 85% of all farmers own only about 2.5 hectares of land or less. This gives then no bargaining power, and they end up getting exploited by the agents. Also, they are not working on a contract-basis, but on a contact-basis. Hence, they have no defense against current exploitation either. On the other hand, for example, Tata Chemicals helps the farmers working with Trent (contractually of-course) in assessing their land, and recommending the most suitable fertilizers and other technologies that could help farmers get a higher output from their land.
  • According to consultancy firm A.T. Kearney, organized retail is currently only 7% of the $435 billion (approx Rs. 21 Lac Crore) Indian retail market but is expected to rise to 21% within the next few years. Food accounts for 70-80% of this. This is led by a consumption class of 400 million people with rising disposable incomes, and a steady rate of urbanization. 

Considering the above numbers, the case for organized retail is self-imposing. Indian conglomerates such as the Tatas, AV Birla, Reliance, etc have already been trying to strengthen their foothold in the Indian organized retail market. While they and other domestic players like Bharti, Future Group, etc. are already trying to eliminate the intermediaries, their scale of operations is not significant enough to bring about a substantial change in the condition of the farmers, or curb prices on a national scale. Furthermore, they lack adequate experience and technical knowhow in the retail domain to introduce any breakthrough innovations. The international players, on the other hand, can leverage their experience to bring the much needed reforms in the Indian supply-chain network by innovating logistics, introducing cold-storage systems, food-processing, IT systems, etc. 

Thirdly, Micro & Small-Scale Enterprises (MSMEs) will have a direct market to sell to and therefore will reap benefit similar to the farmers. In fact, the challenge for them will be to scale up their operations to meet the demand of these organized retailers. In such a scenario, they too will ramp up production scale and hire more workers. Some might even innovate and adopt newer technologies, thereby generating a larger positive spillover effect in their community.

The fourth benefit of FDI in retail will come in the form of a positive externality of making our workforce more employable. At present, several employers often complain of India’s current workforce lacking several key skills and hence being unemployable. Many workers in the current retail sector will not lose jobs like the politicians have been suggesting, but instead, be hired for their experience & understanding of the Indian consumer, and get trained for the new retail landscape. According to reports from the consultancy firm Boston Consulting Group (BCG), organized retail could right away create about 10 million jobs – 4 million direct and another 6 million indirect jobs. It would generate additional incomes of Rs. 73,000 Cr (approx $14.6 billion), and consumers would save about 1.5 Lac Crore (approx $31.25 billion) annually in their shopping bill. However this is only possible if significant scale is achieved and technology is applied, which is only achievable by allowing FDI in Multi-brand retail. The illustration below shows the current employment generated by Retail trade in some cities. These numbers will only grow post FDI reforms.   

These are just some of the more obvious benefits that we can foresee already, and I am sure there are more too. But there’s more to the retail FDI story than just the numbers I presented. I will do a follow-up post on this topic highlighting the bigger picture, and state my case as to why I feel FDI is going to benefit India. Until then, I leave you with this Illustration which appeared in Hindustan Times, showing how some other countries have opened their doors to FDI in their Retail Industry.